

Office Hours Is Today, And Now We Can Say What It’s About
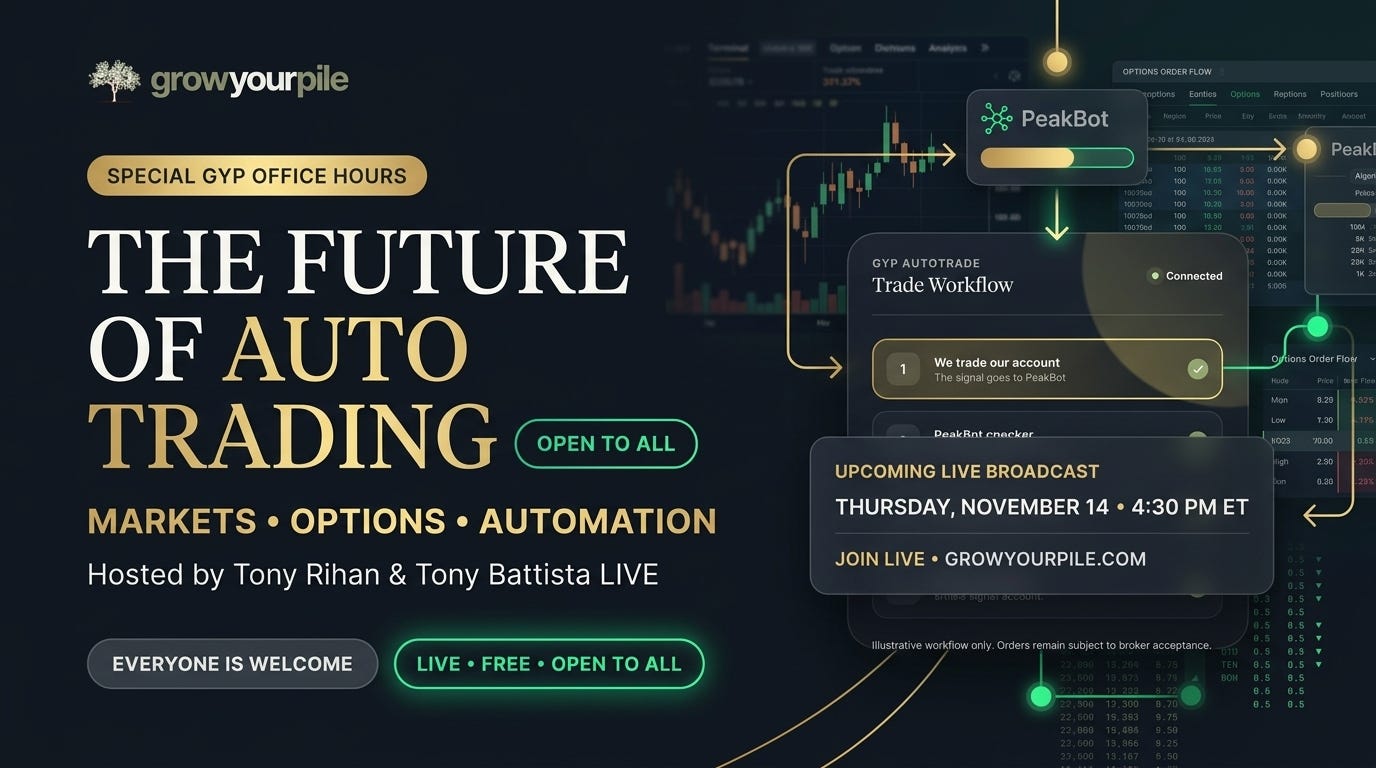
It’s AutoTrade.
A lot of our members have asked us for a way to automate the trades in Portfolios 1 and 2. At 5:00 PM ET today we’ll show you what we’ve put together.
That’s why both portfolios cleaned house on Tuesday. If you’re a member, you saw the alerts.
Two things you should hear from us before the details. It’s optional, and offering it isn’t a recommendation to use it. We’re offering it because people asked, not because we think you need it, and following the alerts and placing the trades yourself is just as valid as it’s always been. And Grow Your Pile has a revenue-sharing agreement with PeakBot, so we earn a share of AutoTrade subscription fees.
The rest we’ll walk through live. Same as Tuesday’s invite, it’s open to everyone, member or not.
📅 Today, Thursday, October 8, 2026
5:00 PM ET · 4:00 PM CT · 2:00 PM PT
A Big Announcement
With Tony Battista & Tony Rihan
streamyard.com/watch/7xA6J2NJ5PZC
Type your question in the chat and we’ll take it live.
Type your question in the chat and we’ll take it live.
See you at five Eastern.
Grow Your Pile Office Hours is educational and is not investment advice or a recommendation to buy or sell any security. Options involve risk and are not suitable for all investors. Strategies discussed carry different risk profiles; long-premium strategies can lose the entire premium paid, and short-premium strategies can produce losses that far exceed the credit received. A short put can require you to buy at the strike and the loss can be substantial in a falling market. Read the Characteristics and Risks of Standardized Options before trading.
Oil Did The Talking This Morning
The stock market didn’t make the news today. Oil did. MT Newswires had it before the bell:
“US Equity Futures Fall Pre-Bell as Oil Prices Rise After Trump Says He Does Not Want Iran Deal”
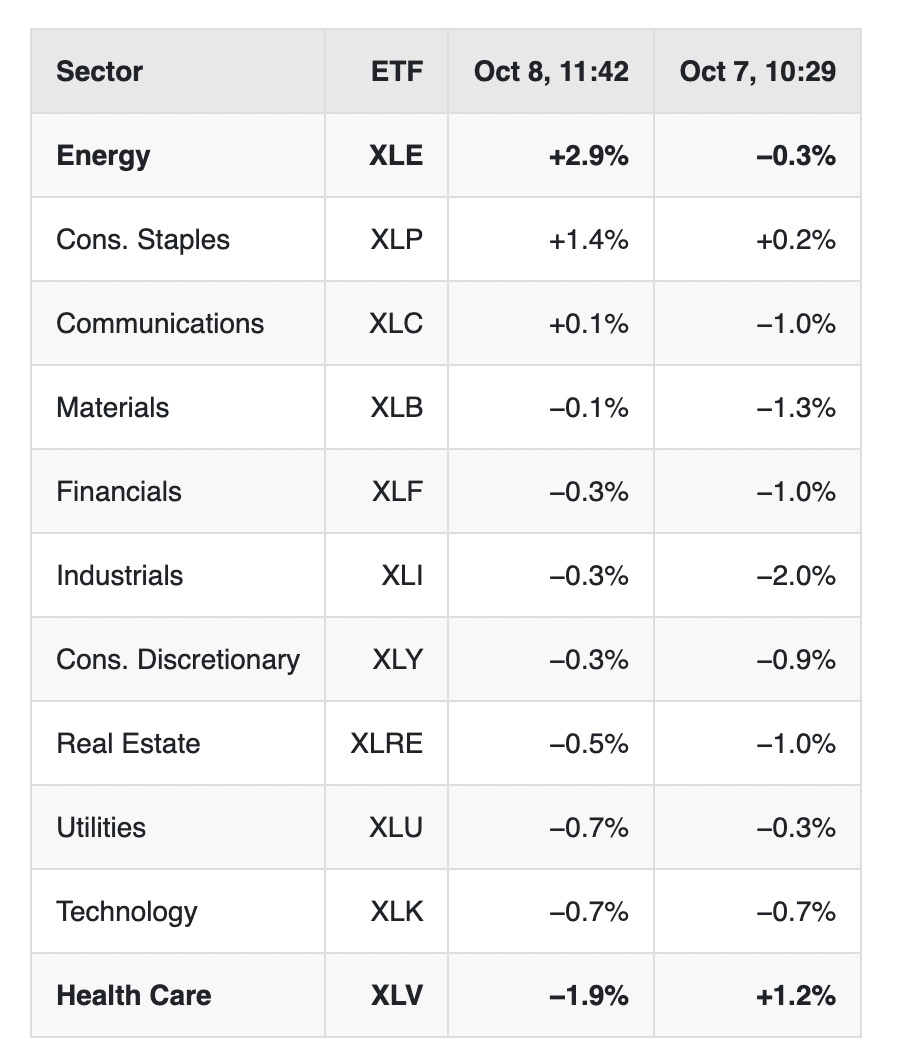
By 11:42 Brent was up 5.4% at $105.62 and US crude was up 5.2% at $92.84. Energy is the best sector on the board, up 2.9%. Staples are second at 1.4%. Only three of the eleven sectors are green, and health care, which led yesterday morning, is last today, down 1.9%.
The indices are lower, but not by much. The S&P's off 0.4%, the Dow too, and the Nasdaq 100 is off 0.7%. The Russell is the worst of the four again, down 1.0%. The VIX is 15.58.
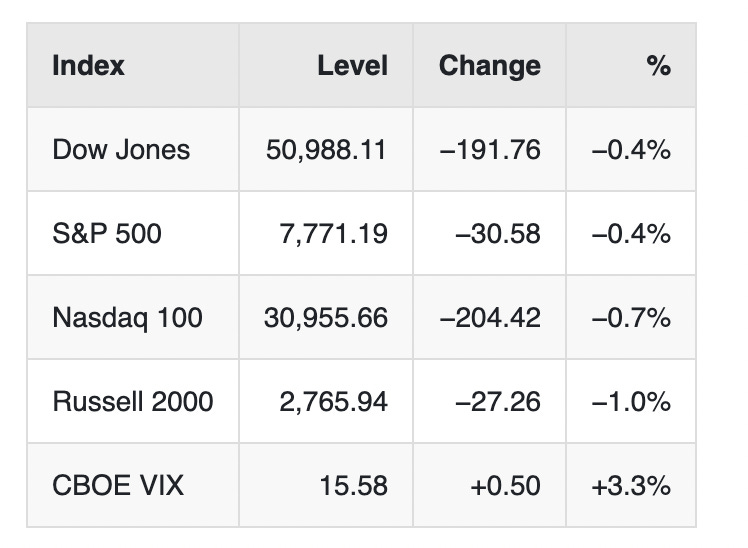
A five percent day in crude with the S&P down four tenths of a percent looks like an irritated market more than a frightened one. The more useful thing is where the money went. Into energy and staples. Out of small caps, and out of the chip names that were green yesterday morning.
Charlie Bilello noted on Tuesday that the S&P “closed above 7,800 today for the first time, hitting its 28th all-time high of the year.” Two sessions later it’s at 7,771.19. Close enough that we wouldn’t call today a break.
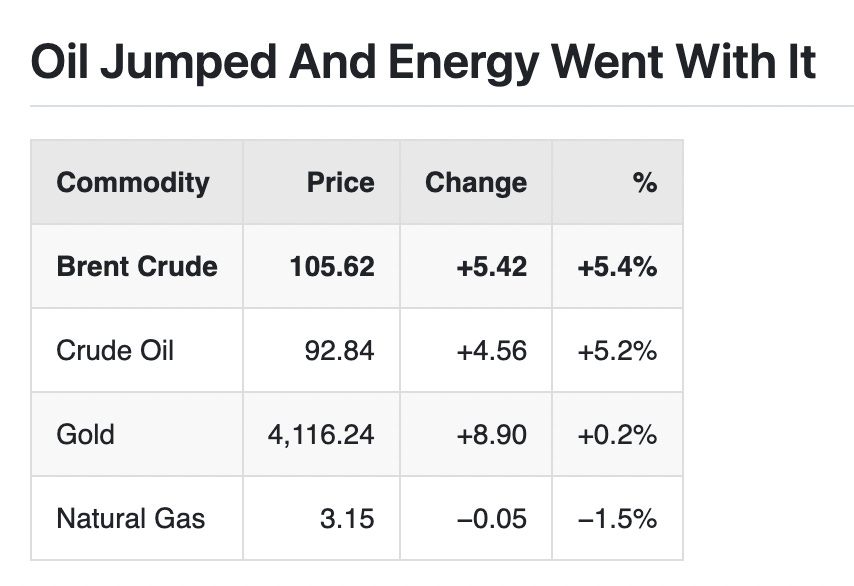
Brent’s up $5.42. On the year it’s up 73.55%, and it’s still 8.37% under its 52-week high of $115.25. Natural gas is the one going the other way, down 1.5%. The weekly storage number was on the wire as “85 VS 64 PREVIOUS; EST 82.”
The energy fund, XLE, is up 2.9% on the day and 5.96% on the week, and it’s 1.52% under its own 52-week high. It’s up 45.75% this year.
Keith McCullough flagged one name this morning: “$MPC remains a big breakout name,” he wrote, in one of his own products. The card on his post had MPC up 5.30%.
The rest of the oil news came in pieces. From the wire:
“UKRAINE SAYS IT HIT RUSSIA’S OMSK OIL REFINERY”
“US MILITARY BRIEFED INTERNATIONAL SHIPPING PARTNERS ON THE STRAIT OF HORMUZ ON THURSDAY -CENTCOM”
Another wire’s version of that briefing said “Leaders highlighted building momentum for freedom of navigation as commercial traffic flow increases.” There was also “MOST OWNERSHIP IN US RUSSIA OIL DEAL TO GO TO MIDEAST FUNDS:NYT” and “US PUBLISHES DIESEL EXECUTIVE ORDER IN FEDERAL REGISTER.”
Our read: the CENTCOM line is the opposite of a supply scare. More ships moving through Hormuz, not fewer. Brent’s up 5.4% anyway. On the same morning, the market is giving the President’s line more weight than the military’s.
The Long End Is A Little Calmer Than Yesterday
You’d expect a five percent oil day to push long yields up. Compared with yesterday morning, it hasn’t.
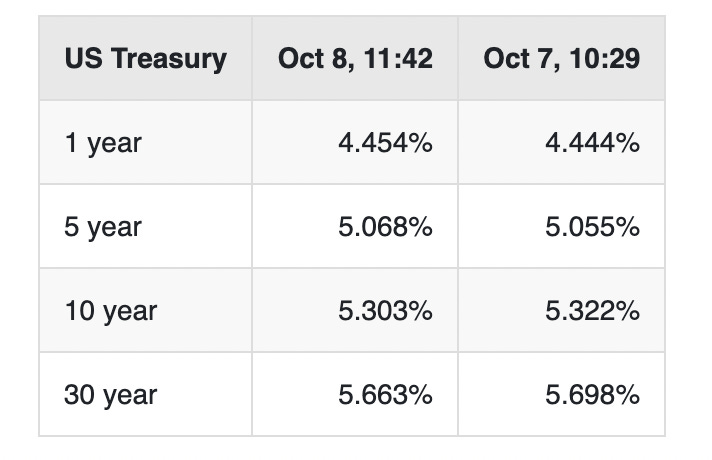
The ten-year is 5.303%, about two basis points below where it was at 10:29 yesterday. The thirty-year is 5.663%, three and a half lower. The one-year and five-year are each about a basis point higher. TLT is up 0.19% and still 16.15% under its 52-week high. These are two morning readings taken at different times of day, so treat it as a lean, not a trend.
The Congressional Budget Office’s Swagel was on the wire with two lines that pull in different directions:
“CBO’S SWAGEL SEES FISCAL TRAJECTORY PUTTING PRESSURE ON RATES”
“CBO’S SWAGEL: DEBT CONCERN IMPACT ON YIELDS IS SMALL”
And on growth:
“CBO’S SWAGEL: NEED 5%-6% GDP GAINS TO STABILIZE DEBT VIA GROWTH”
“SWAGEL: UNLIKELY GROWTH ALONE CAN STABILIZE DEBT TRAJECTORY”
Our read: both rate lines can be true at once. The direction of the debt leans on rates over years, while on any single day it isn’t what moves the ten-year. And he’s saying growth probably can’t fix it alone.
The weekly claims were fine. Liz Ann Sonders:
“Initial jobless claims down to 197k vs. 200k est. & 199k prior; continuing claims at 1.716M vs. 1.700M est. & 1.699M prior …”
Fewer new claims than expected, more people still collecting than expected. She also posted the Atlanta Fed’s GDPNow, which she calls “a ‘nowcast,’ not a forecast,” at +3.6% for the third quarter, down from +3.7% on October 6.
Housing And The Price Of Borrowing
Yesterday it was RPM’s chief executive on housing turnover at a 40-year low. Today Danielle DiMartino Booth had this about sellers:
“All bets are off if sellers finally capitulate. And I mean FINALLY. All those bidding wars (remember those?) created the most stubborn home sellers in history. And no, it wasn’t just golden handcuffs of ultra-low mortgage rates. Otherwise HELOCs wouldn’t be flying off the shelves”
She was answering Jason Lewris, who’d written: “Investors are contributing more to the for sale side of housing inventory than at any point this year. Earlier this year, they only accounted for 12% of all homes for sale. Today, that is 16.2%.”
She also passed along a post from Melody Wright without adding words of her own. The words are Wright’s:
“Pending sales data is looking pretty scary while the 10-year treasury and mortgage rates remain elevated. The delinquency rate (from historic lows) is screaming higher YoY. Delinquency is about flows and roll-rates so this is the number to watch”
And Sonders had the consumer’s side of it:
“Financing costs rose in August … average interest rate on credit cards with assessed interest reached 22.36%; average interest rate on a 5-year new car loan rose to 7.54%”
Our read: sellers who won’t sell, borrowing against the house through HELOCs instead, and a card rate of 22.36%. With the ten-year above 5.3%, nothing in today’s numbers says any of those rates is about to come down.
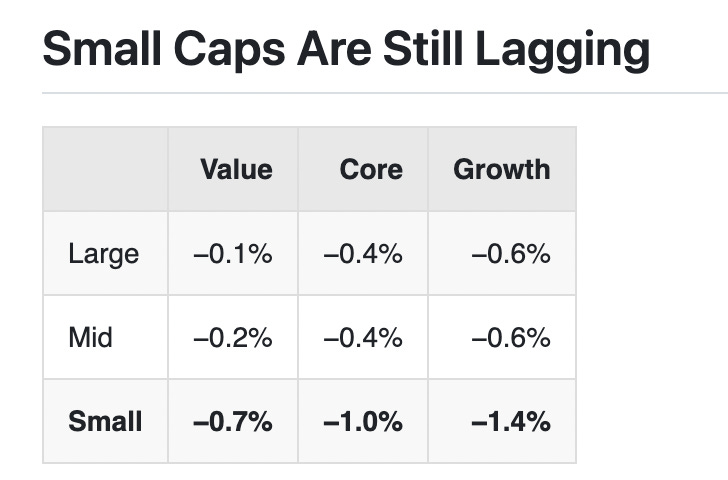
Every box is red again. Small growth is the worst, down 1.4%. Large value is the best, down a tenth. Growth is behind value in every row, and small caps are behind mid caps in every column. Yesterday morning it was mid caps taking the worst of it. Today it’s the small ones.
The one-month numbers show how long this has been going on:
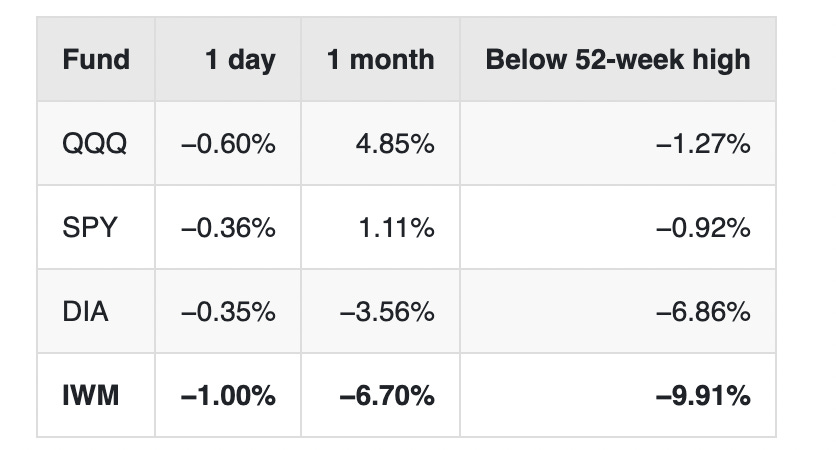
Over the past month QQQ is up 4.85% and IWM is down 6.70%. SPY is 0.92% off its high. IWM is 9.91% off its.
On Wednesday Doug Kass shared Seabreeze Partners’ post, “What?! Say it isn’t Crow,” on a piece titled “Another Day That the Russell Isn’t Crowing.”
Yesterday’s Green Chips Are Red Today
Yesterday morning Intel, Sandisk and Micron were the green ones. This morning all three are down more than 2%.
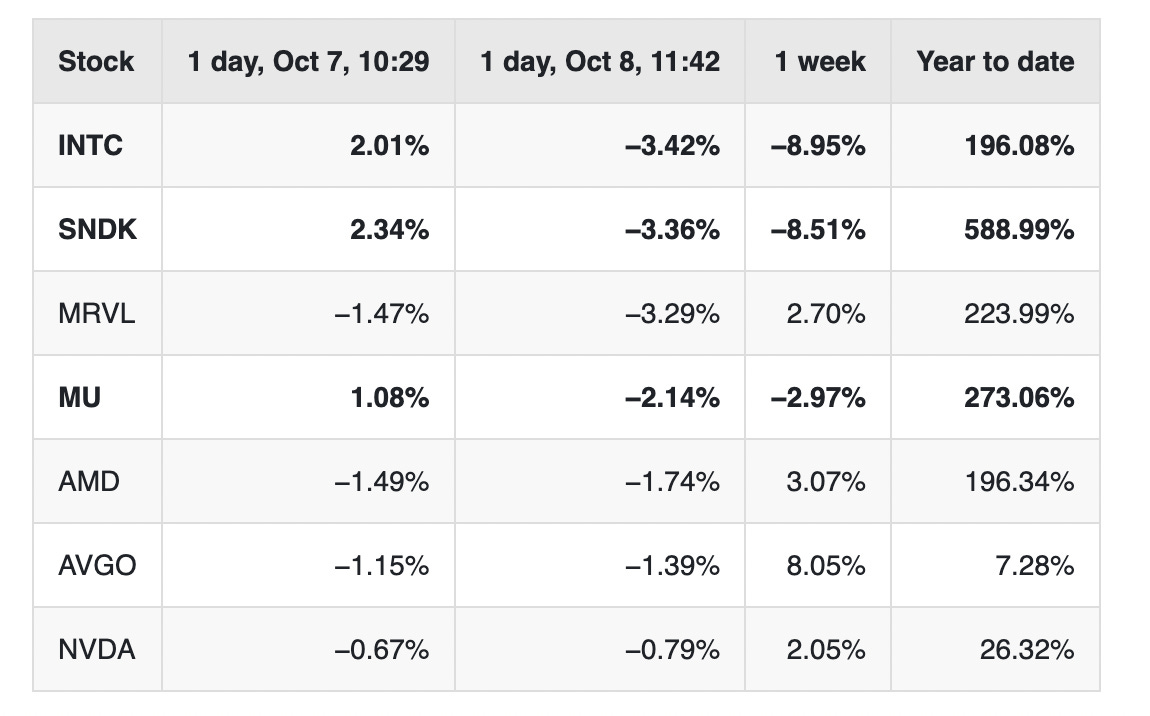
Intel went from up 2.01% to down 3.42%, Sandisk from up 2.34% to down 3.36%, Micron from up 1.08% to down 2.14%. Marvell is down 3.29% after being down 1.47% yesterday morning. Intel and Sandisk are each down more than 8% on the week. On the year, though, Intel’s still up 196.08% and Sandisk 588.99%. When a stock is up that much, a few bad days don’t change the year, but they do tell you how fast the money can leave.
NVIDIA’s off 0.79%. The wire had “$NVDA - NVIDIA COMMITS $1 BILLION TO ADVANCE US SCIENCE OVER THE NEXT FIVE YEARS.”
DiMartino Booth had a line on where the AI money comes from:
“AI will change something! But it’s more likely to ‘just’ be tacking an extra trillion onto the $16 trillion corporate debt market. Whee!”
Across the 22 stocks and funds on our watchlist, five are green: AAPL, GLD, MSFT, NFLX and TLT.
The Retail Crowd Got Braver
From Sonders again, on the AAII survey for the week ending October 7:
“Bullish sentiment jumped to 40.3% vs. 34.6% in latest @AAIISentiment (week ending 10/7/26) while bearish sentiment declined sharply to 39.0% from 46.5% the prior week …”
Bulls ahead of bears by 1.3 points, a week after bears led by 11.9. That survey closed before this morning’s oil headline. The VIX is 15.58, near yesterday morning’s 15.70 and down at the low end of its 52-week range of 13.38 to 35.30. Our read: protection isn’t being bid hard, and the crowd’s in a better mood than it was a week ago.
Around The World
Charlie Bilello, on Wednesday:
“Global Central Bank Update: -India hiked rates for the first time since 2023, 25 bp increase up to 5.50%.”
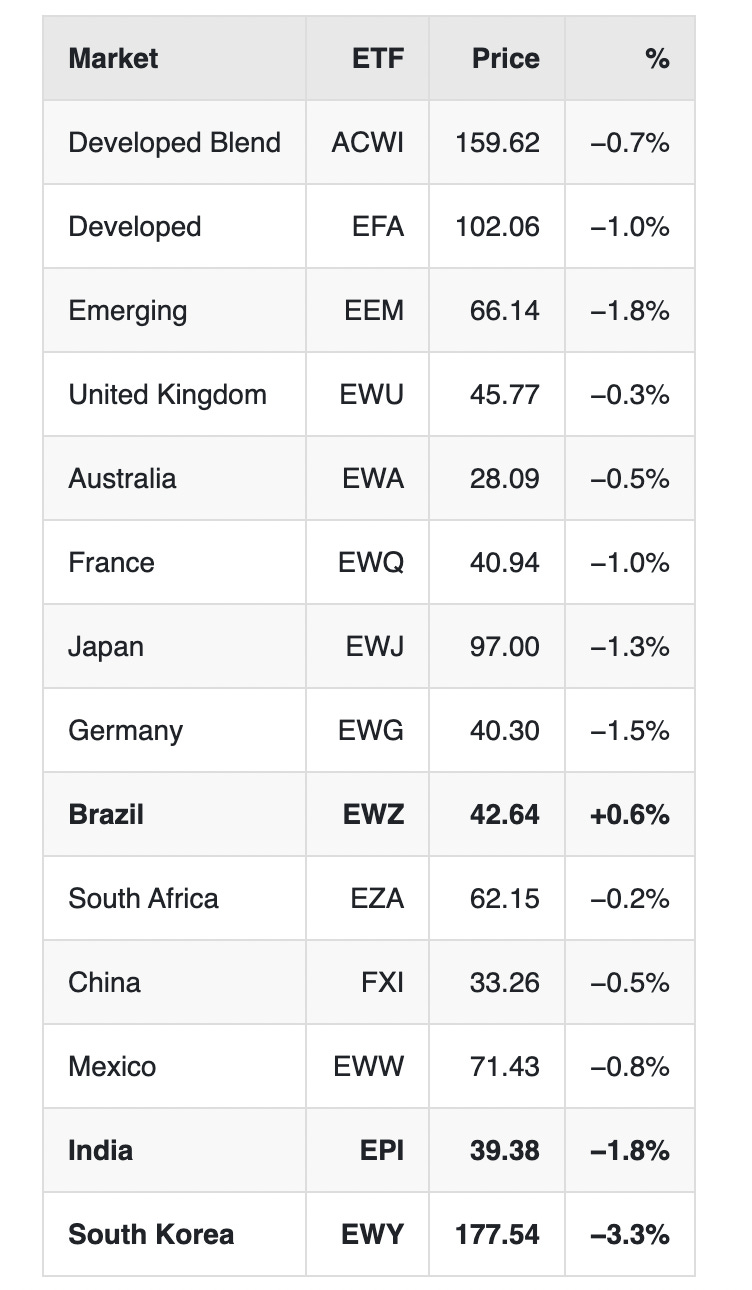
India’s fund is down 1.8% this morning. It isn’t the worst on the board: South Korea’s down 3.3%. Brazil is the only green one, up 0.6%. That’s one of fourteen.
Bond yields abroad:
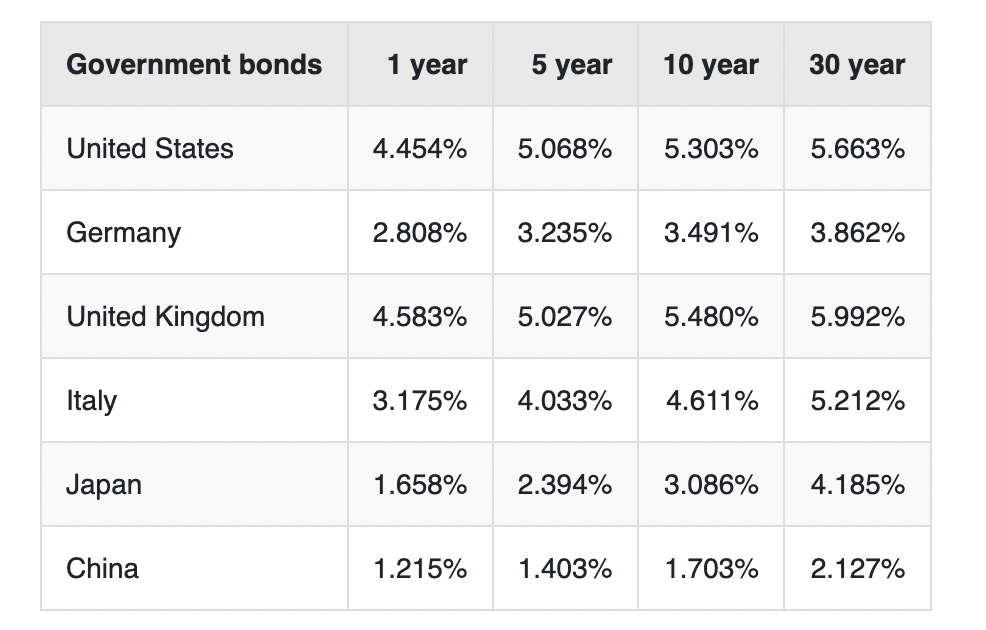
Britain’s thirty-year is 5.992%, a touch above yesterday morning’s 5.983%. Its ten-year pays 5.480% against our 5.303%.
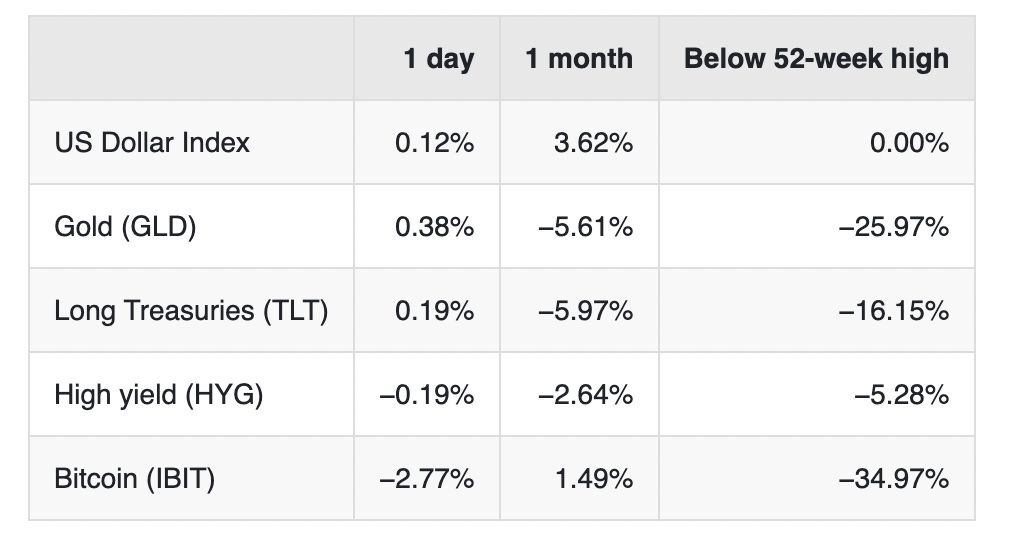
The dollar index is at 102.36, which is its 52-week high. Bitcoin’s down 2.8% at $81,067.28. And gold is up 0.2% at $4,116.24, so yesterday’s question got a small answer, at least as of 11:42.
Also On The Wire
Washington spent the morning on work visas. From the wire: “US VP VANCE: THE US IS REFORMING H-1B AND J-1 VISA PROGRAMS,” then “$MSFT $ADBE - LABOR SECRETARY SAYS IS SUSPENDING SOME OF THE LARGEST IT SOURCING FIRMS IN THE WORLD FROM LABOR CERTIFICATION PROGRAM INCLUDING MICROSOFT AND ADOBE,” and “US SUSPENDS IMMIGRATION PROGRAM FOR COGNIZANT, INFOSYS, TATA.”
And “UKRAINE’S ZELENSKIY: UKRAINIAN TEAM IS ON ITS WAY TO US FOR TALKS.”
Bottom Line
Written off 11:42 AM ET prices, with the afternoon still to come. In the order we’d rank it:
Oil is the story. Brent’s up 5.4% at $105.62 after Trump said he doesn’t want an Iran deal, and energy is the best sector by a wide margin. That’s with CENTCOM talking about more traffic through Hormuz on the same wire.
Rates eased a touch at the long end compared with yesterday morning, ten-year 5.303%, thirty-year 5.663%. The CBO’s Swagel says the fiscal path puts pressure on rates, that the impact of debt concern on yields is small, and that growth alone is unlikely to fix the debt. Initial claims beat, and GDPNow is 3.6%.
The smaller and the hotter names are where the selling is. The Russell’s down 1.0% and IWM is off 6.70% over the past month. Every factor box is red, and yesterday’s three green chips are down between 2.14% and 3.42%.
Housing and borrowing costs keep showing up. Stubborn sellers and HELOCs from DiMartino Booth, delinquencies from Wright, 22.36% on credit cards and 7.54% on a car loan from Sonders.
And retail sentiment turned up in the latest AAII week, with the VIX in the mid-teens. Today’s tape hasn’t asked anyone to change their mind yet.
See you at Office Hours at 5:00 PM ET.
Disclaimer
This is not investment advice. Nothing in this letter is a recommendation to buy or sell any security. Grow Your Pile and Squared T Capital publish what we do in our own accounts for education. Options involve substantial risk and are not suitable for every investor. A short put can require you to buy stock at the strike price and can lose more than the premium collected. Past results do not predict future results. Do your own work and consider speaking with a licensed advisor about your circumstances.
Past performance is not indicative of future results, and results shown are those of our own accounts and are not representative of any subscriber’s results. Read the Characteristics and Risks of Standardized Options before trading.
Tony Rihan and Tony Battista Grow Your Pile · Squared T Capital
Every options trade in Portfolio 1 and Portfolio 2 goes out win or lose, with entry, exit and running P&L. Portfolio 3 publishes its full weights. All of it is at growyourpile.com.