A late-morning read, written with the market open.
Chips Down, Platforms Up
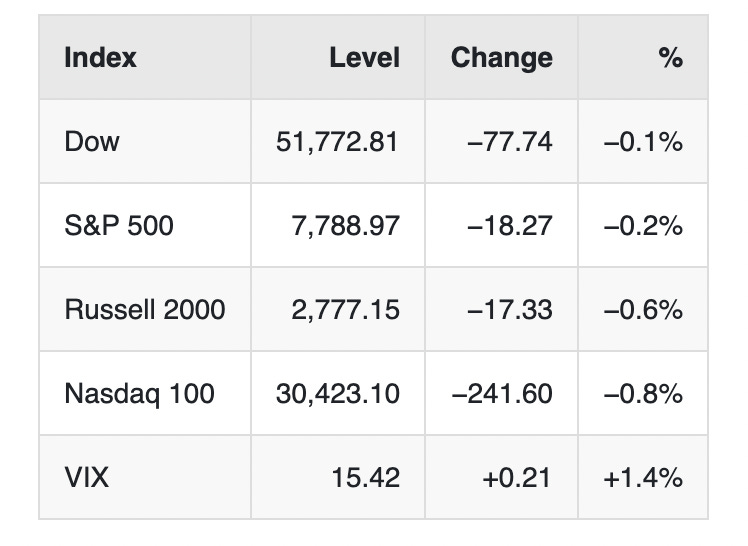
If all you checked this morning was the S&P, you’d call it a quiet Tuesday. It’s down 0.2%. Underneath, there are two markets going in opposite directions.
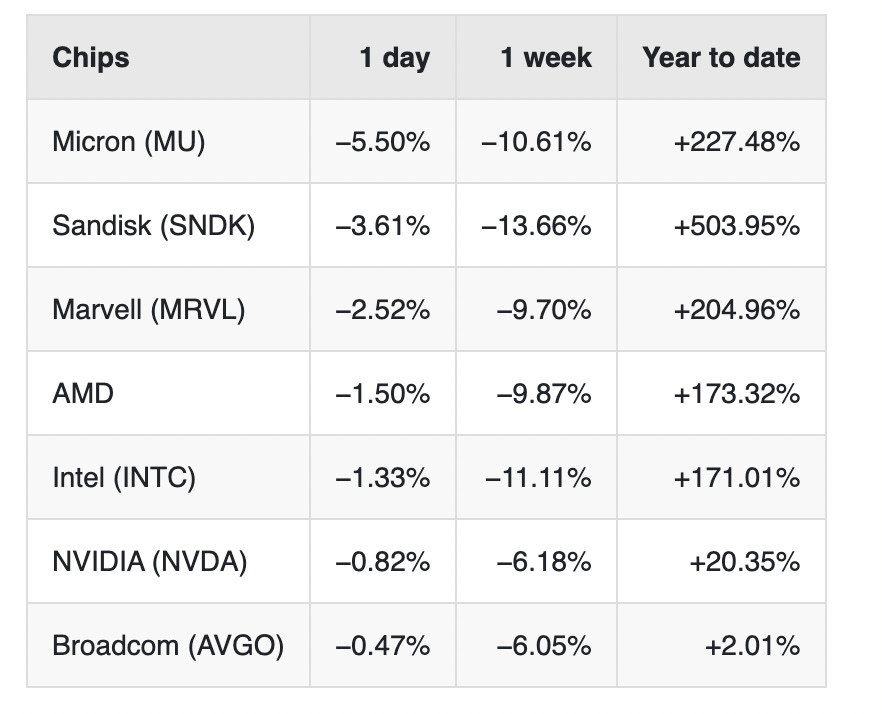
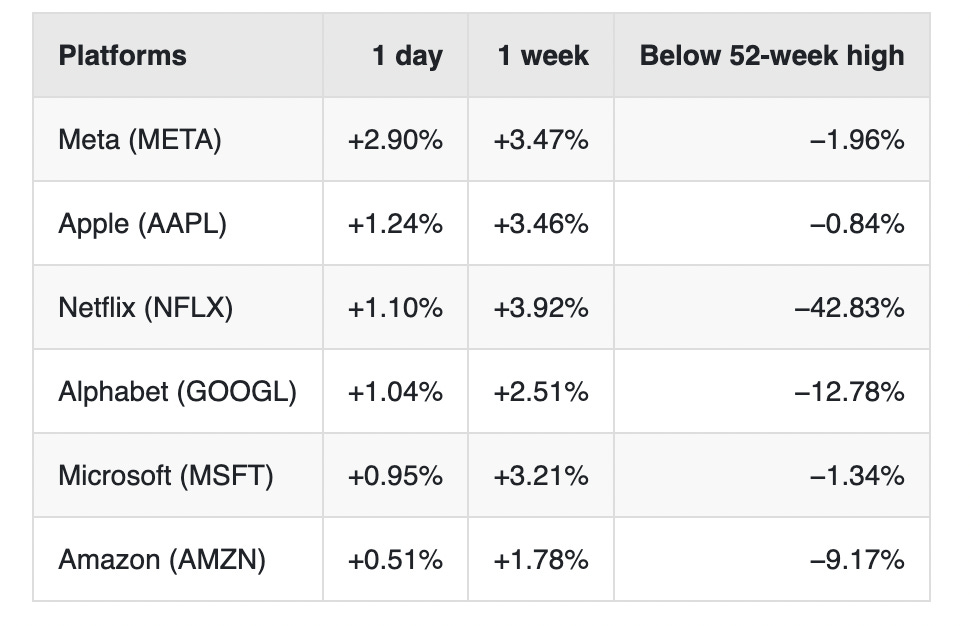
The chip names are being sold. Micron’s down 5.50%, Sandisk 3.61%, Marvell 2.52%, AMD 1.50% and Intel 1.33%. Meanwhile the big platform names are green: Meta’s up 2.90%, Apple 1.24%, Netflix 1.10%, Alphabet 1.04%, Microsoft 0.95% and Amazon 0.51%.
The chip weakness showed up before the open. MT Newswires at 9:10:
All seven are down on the week as well. Sandisk's off 13.66% for the week, Intel 11.11%, Micron 10.61%. Now look at the last column. Sandisk is still up 503.95% this year and Micron 227.48%. A week like this one barely dents a year like that. It's also exactly the kind of week a year like that should prepare you for.
Apple’s 0.84% under its 52-week high, Microsoft 1.34% and Meta 1.96%. Netflix is green too, and it’s 42.83% under its own high, so the green side isn’t one trade either.
NVIDIA’s down 0.82%. First Squawk had Jensen Huang saying NVIDIA “HAS INVESTED $8B ACROSS EUROPE IN THE LAST YEAR.” And Doug Kass wrote on Monday that he’s still short NVIDIA from $238. That’s his own position.
On the index level, the Nasdaq 100’s down 0.8%, more than the S&P or the Dow.
Bank Earnings Morning, And JPM Went Green Anyway
The pre-market wire had it plainly. MT Newswires at 8:48:
“Update: US Equity Futures Mixed Pre-Bell as Traders Assess Major Bank Earnings”
JPMorgan’s numbers were the ones people argued about. Doug Kass has argued that “bank/financial stocks should be avoided,” and before the open he wrote that JPM “leads the EPS parade by missing both top and bottom line,” with the shares down $12.
Keith McCullough posted Hedgeye’s take from their show, The Call. They had JPM at 5.57 against the 5.93 the Street was looking for, and said the numbers “are not great, they aren’t quite terrible.” They also flagged a “one time 18 cent per share loss on the net investment securities” before the post cuts off.
Then the stock turned. A follower told Kass JPM had gone green, and he answered:
“I actually purchased stock (for a short term rental) on this morning’s decline …”
The card on his posts had JPM at $338.07, up 1.13%, around noon. Two voices called it a miss, and by midday the shares were green.
Goldman’s morning went the other way. From First Squawk:
“GOLDMAN SHARES TURN NEGATIVE; HAD BEEN UP 4.1%”
“GOLDMAN SACHS CEO: NO SUCCESSION TRANSITION OR TIMELINE”
And Wells Fargo’s chief executive, also via First Squawk:
“WELLS FARGO CEO: US ECONOMIC GROWTH CONTINUES TO BE STRONG; UNCERTAINTY PERSISTS DUE TO STICKY INFLATION, CONFLICT IN MIDDLE EAST, PERSISTENT FISCAL DEFICITS, VOLATILE ENERGY MARKETS”
The financials fund, XLF, is up 0.3% this morning and 2.42% on the week.
Home Sales Beat, And More Sellers Are Cutting
September’s existing home sales came in better than expected. Walter Bloomberg’s headline:
“U.S. EXISTING HOME SALES BEAT EXPECTATIONS AS PRICES HIT SEPTEMBER RECORD”
Sales ran at an annualized 3.99 million against 3.95 million expected, up 1.5% on the month. Liz Ann Sonders had the estimate for that monthly change at minus 0.8%, and August’s change revised down to minus 3.2% from minus 2.0%. August’s sales level was revised to 3.93 million from 3.98 million. The median price was $417,500, up 1.3% from a year ago, and inventory was 1.60 million homes, 4.8 months’ supply.
Danielle DiMartino Booth called it the “2nd sub 4M SAAR” and broke it down by region: sales in the South and West rose 2.8%, the Midwest was flat and the Northeast fell. She also posted this line from Bloomberg’s report, which doesn’t name who said it:
“Q4 outlook for closing activity will clearly be down, maybe even measurably down. We’re seeing more delays in contracts w/rising rates.”
On price, she passed along Jason Lewris’s count from Monday morning. Lewris wrote that 43.4% of all US homes for sale are now undergoing price cuts, “the highest read all year, up an additional 70 basis points from this time last week.” Her comment on it:
“Note that many straggler markets are beginning to come under pressure.”
She also shared Charlie Bilello’s post from Monday that “There are now over 1.16 million homes for sale in the US, the highest inventory since 2019.” That’s his count of listings, which is a different measure from the 1.60 million in the sales report. Her take on where this goes: “the pendulum will swing back.”
Our read: a sales number that beat, a median price still up on the year, and a growing share of sellers cutting their price. Buyers and sellers are still working out where the price is.
Energy’s Within A Penny Of Its High
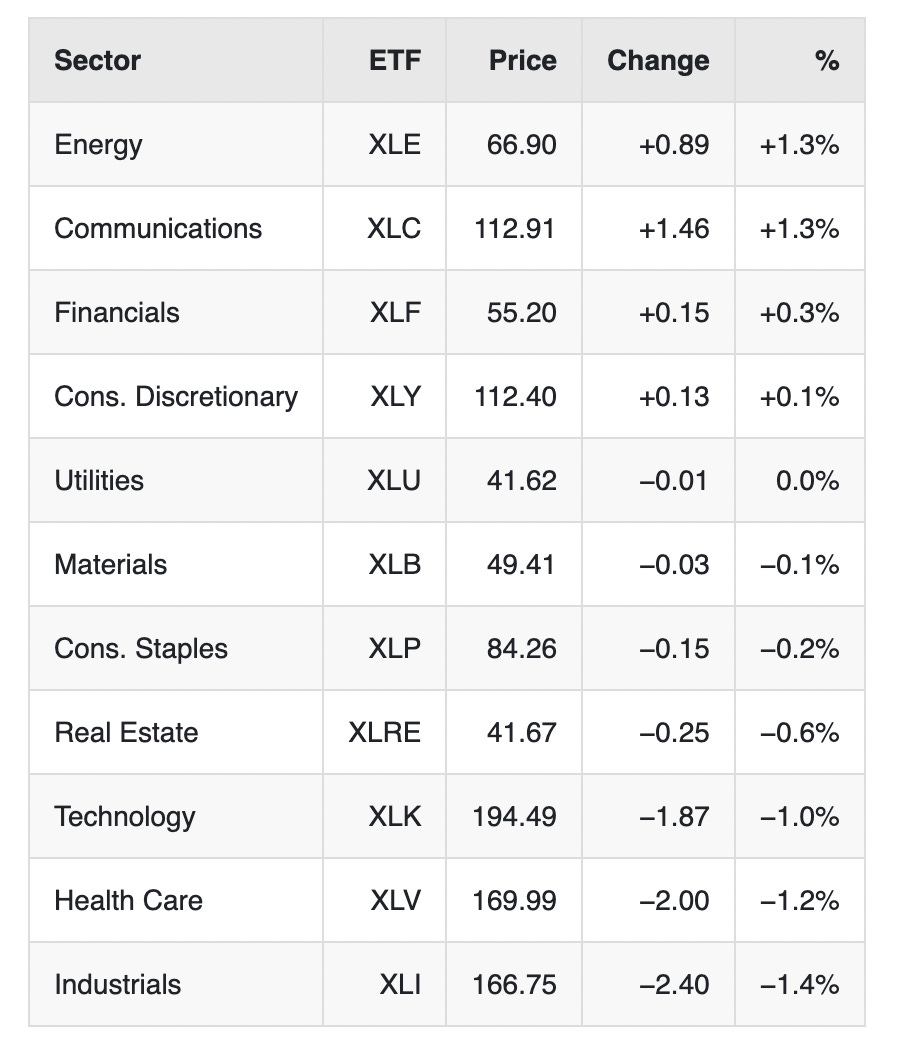
Four of the eleven sectors are green. Energy and communications lead, up 1.3% each. Financials are up 0.3% and consumer discretionary 0.1%. Utilities are flat, down a cent. Industrials are the weakest, down 1.4%, with health care down 1.2% and technology 1.0%.
XLE is within a penny of its 52-week high of $66.90. It’s up 5.42% on the week and 49.61% on the year.
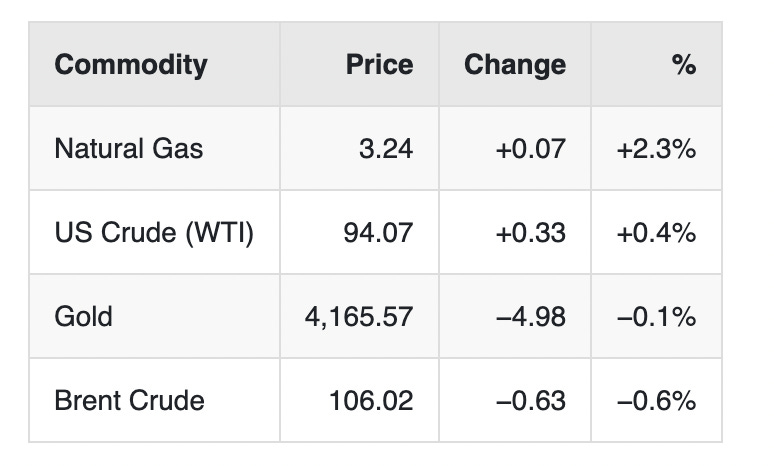
The barrels themselves are split. Brent’s down 0.6% at $106.02 and US crude is up 0.4% at $94.07. Natural gas is up 2.3%. Brent’s still up 74.25% this year.
Two more energy items were on the wire this morning. From Walter Bloomberg:
“U.S. diesel futures are up 2.1% to $4.8239 per gallon, despite tax relief measures and the lifting of sanctions on Russian diesel.”
And from First Squawk:
“IRANIAN NAVY: A VIOLATING OIL TANKER CAUGHT FIRE EAST OF THE STRAIT OF HORMUZ - IRNA.
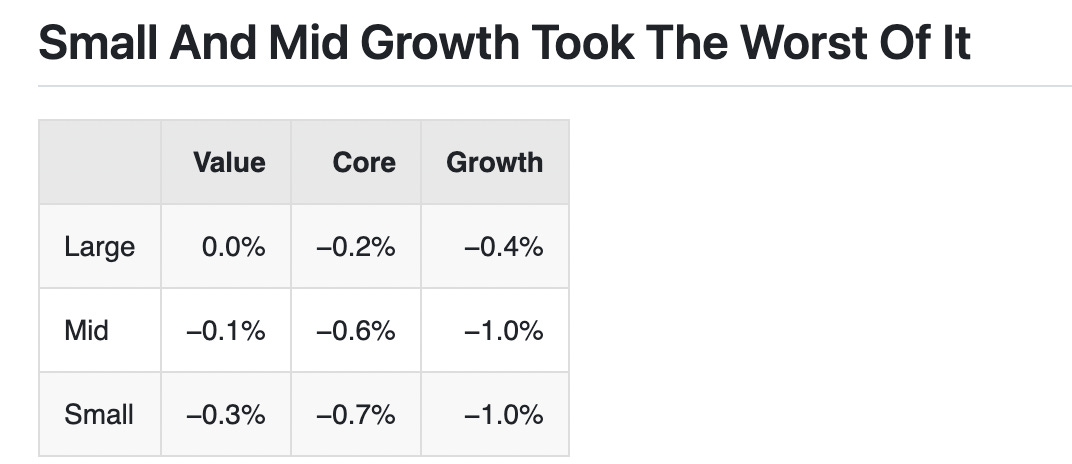
Mid growth and small growth are both down 1.0%. Large value is flat. Growth trails value in every row.
Keith McCullough on the small caps this morning:
“Russell 2000s Drawdown Continues To Fresh 3-Month Lows”
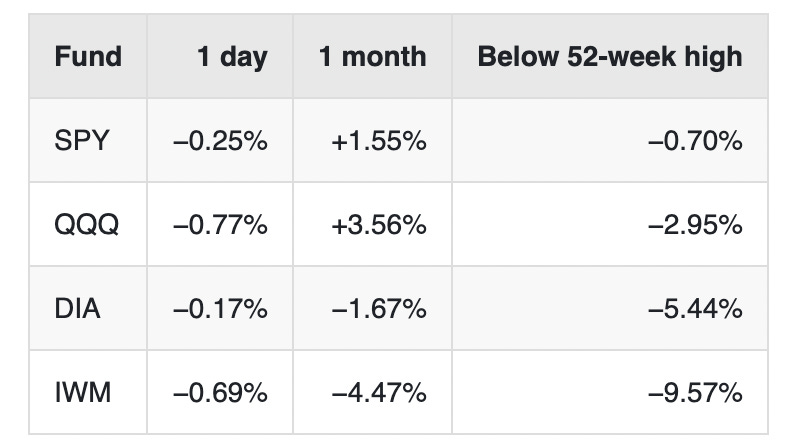
SPY is 0.70% under its 52-week high. IWM is 9.57% under its. Over the past month QQQ is up 3.56% and IWM is down 4.47%. On the year, the Nasdaq 100’s up 20.49%, the S&P 13.78%, the Russell 11.89% and the Dow 7.72%.
The VIX is 15.42, up 0.21. Its 52-week range runs from 13.38 to 35.30, so it’s sitting near the floor. Kass on Monday evening, on a different gauge:
“Just what I thought the S and P Short Range Oscillator slipped to -0.66% - that’s virtually neutral after being -6% a week or so ago.”
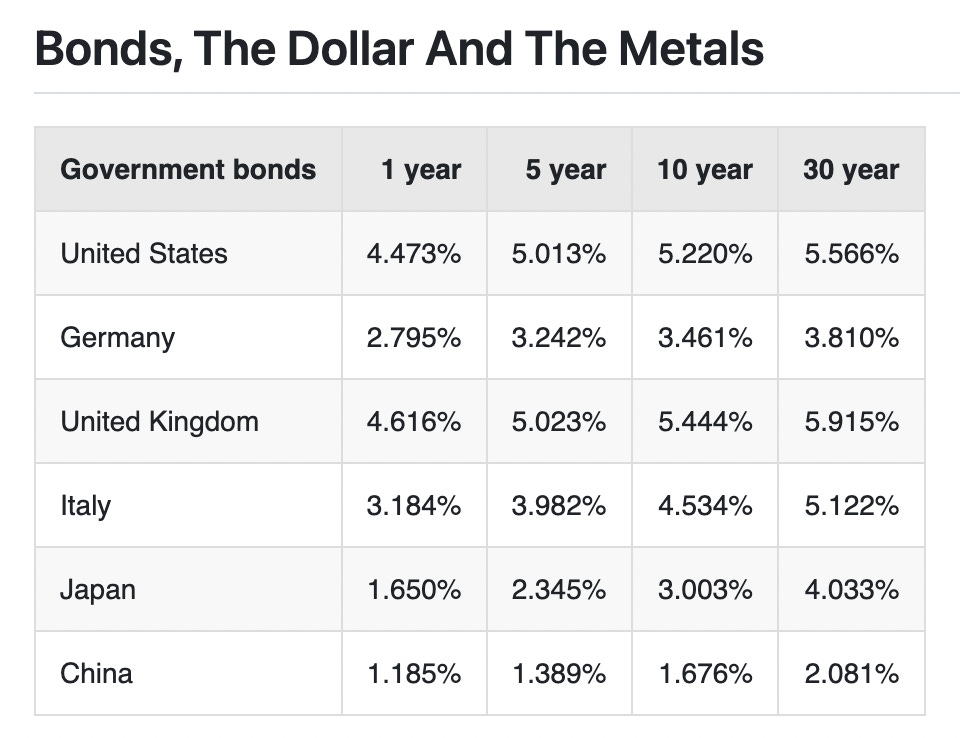
The US ten-year is 5.220% and the thirty-year 5.566%. Britain’s thirty-year is higher than ours at 5.915%.
Walter Bloomberg had BMO’s view on the long end:
“INVESTORS PILE INTO LONG-TERM U.S. TREASURIES AHEAD OF CPI AND FED DECISION”
“Investors are favoring longer-term Treasuries, pushing long-term yields lower faster than short-term rates, according to BMO.”
TLT is up 0.43% this morning and 1.43% on the week.
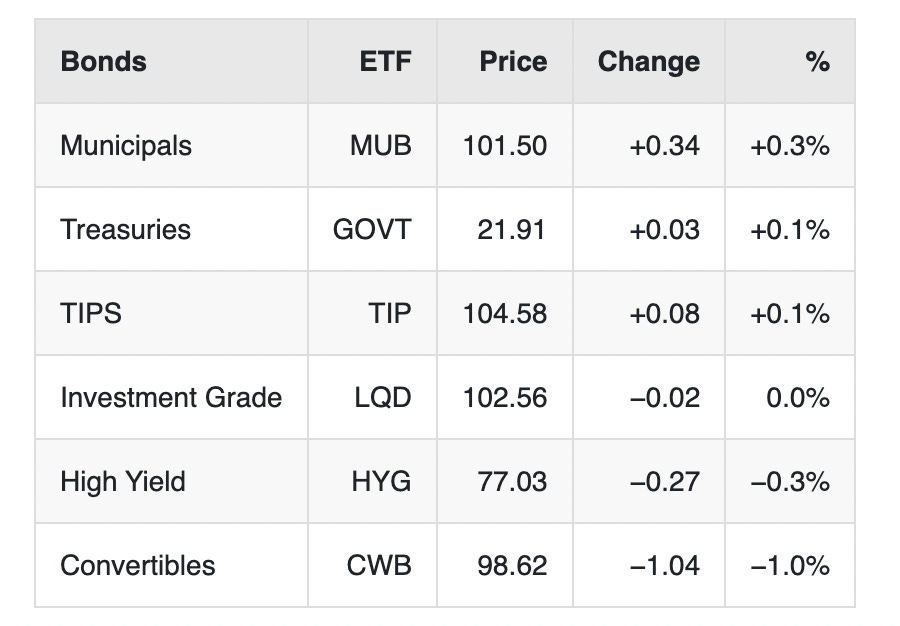
Convertibles are the weakest line on the bond board, down 1.0%. High yield’s off 0.3%. Investment grade is flat, down two cents.
The dollar index is down 0.31% at 102.27, and it’s 0.31% under its 52-week high. The euro and the pound are each up 0.3%. Dollar-yen is 158.39, down 0.1%.
Silver’s the mover in metals. SLV is down 1.41% and 51.21% under its 52-week high. It’s down 16.83% this year and still up 13.37% from a year ago. Gold’s down a tenth at $4,165.57, and GLD sits 25.14% under its high. Bitcoin’s up 0.6% at $83,485.35, 28.35% under its high.
Around The World
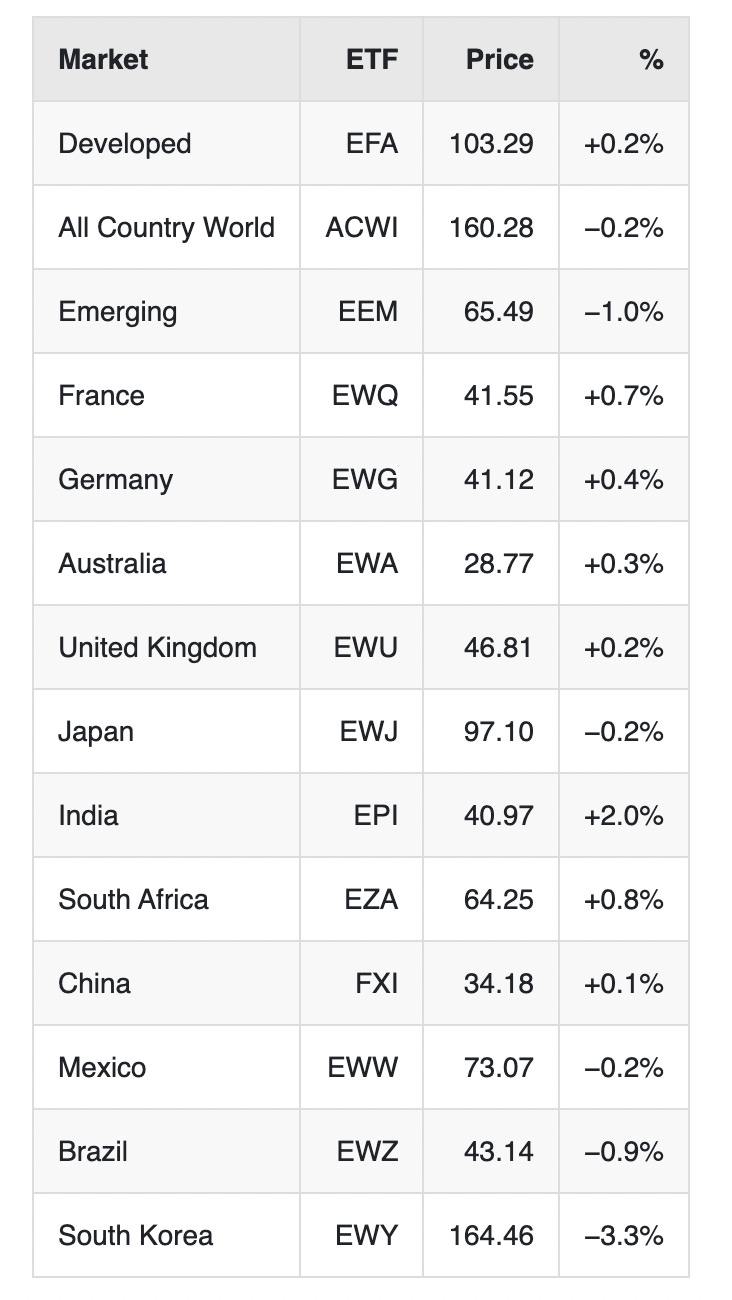
South Korea’s fund, EWY, is down 3.3%, the worst of the fourteen on our board. McCullough had the overnight move in Seoul:
“CRASH: South Korea’s KOSPI got smoked for another -5.5% loss overnight, taking its stock market crash to -33.8% from its #MOAB Peak”
Eight of the fourteen are green. India’s the best, up 2.0%, and France, Germany and Britain are all up.
Sonders had the IMF’s new outlook:
“Per @IMFnews latest World Economic Outlook, the global economy is projected to grow at 3.1% in 2026 (up from 3.0% expected in July) before rebounding to 3.4% (unchanged from July) in 2027.”
And DiMartino Booth reposted Daniel Lacalle on China’s borrowing costs:
“China’s debt interest costs are soaring above U.S. levels and growing faster than any other budget category as Beijing struggles to prop up growth.”
“19% of Beijing’s spending is earmarked for interest on debt.”
Stocks Against Bonds, Seven Years Running
The post we’d keep from today is Charlie Bilello’s:
“The gap between stock and bond returns has never been wider.
Last 7 years:
S&P 500: +16.9% annualized
US Bonds: +0.4% annualized
That’s a nearly 17% spread, the largest on record. Investors shouldn’t expect a repeat over the next 7 years.”
His last sentence is the one to sit with. Seven years is long enough for a number to start feeling normal, and nothing about this morning’s 5.220% ten-year says the next seven have to look like the last.
Also On The Wire
From First Squawk: “INDIA EXTERNAL AFFAIRS MINISTER SAYS INDIA, US OFFICIALS ARE ‘IRONING OUT’ TRADE DEAL TALKS; NEGOTIATIONS ARE HEADING IN RIGHT DIRECTION.”
Sonders on jobs: “Hiring slowed marginally for the first time in eight weeks with private payrolls adding an average of 24,750 jobs for four-weeks ending Sep. 26 per @adpresearch.”
And on flows: “For week ended 10/9/26, large-cap ETFs led equity inflows, while aggregate bond funds recorded largest inflows within fixed income; thematic strategies experienced largest overall outflows @DataArbor.”
Bottom Line
Written off late-morning prices, so the afternoon can still change the picture. In the order we’d rank it:
Chips are being sold and the platform names are bid. Micron’s down 5.50%, Meta’s up 2.90%, and the S&P sits in between, down 0.2%.
Kass and Hedgeye both called JPM’s quarter a miss, and the card on Kass’s posts had the stock up 1.13% around noon. Goldman’s shares turned negative after being up 4.1%.
Existing home sales beat at 3.99 million, while Lewris counts 43.4% of homes for sale with price cuts.
Energy’s within a penny of its 52-week high. Small and mid growth are the weakest boxes on the grid. Korea’s fund is down 3.3%, and the VIX is 15.42.
Disclaimer
This is not investment advice. Nothing in this letter is a recommendation to buy or sell any security. Grow Your Pile and Squared T Capital publish what we do in our own accounts for education. Options involve substantial risk and are not suitable for every investor. A short put can require you to buy stock at the strike price and can lose more than the premium collected. Past results do not predict future results. Do your own work and consider speaking with a licensed advisor about your circumstances.
Past performance is not indicative of future results, and results shown are those of our own accounts and are not representative of any subscriber’s results. Read the Characteristics and Risks of Standardized Options before trading.
Tony Rihan and Tony Battista Grow Your Pile · Squared T Capital
Every options trade in Portfolio 1 and Portfolio 2 goes out win or lose, with entry, exit and running P&L. Portfolio 3 publishes its full weights. All of it is at growyourpile.com.