

Monday the oil story was diplomatic. Qatar was brokering, Iran might deal, and crude fell four and a half percent on the possibility. Tuesday it drifted another one and a quarter percent to settle at $94.59. Then it gapped.
As this is written, before the US open, WTI is trading near $89.60 — roughly five dollars below Tuesday’s settle in a single overnight session. Iran says half the damaged South Pars gas capacity has resumed production, and the FT has crude on its longest losing streak in more than twelve months.
Barrels are physically returning. That is a different thing from a headline about talks, and the tape is repricing it while New York sleeps.
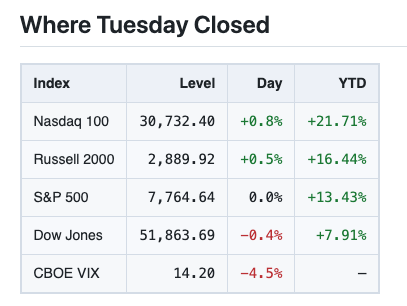
Four indices, four different answers, and nearly fourteen points between the best and worst of them on the year. The Nasdaq 100 is up 21.71% and the Dow is up 7.91%. That gap is the market of 2026 in one line.
Monday the VIX rose on a day the S&P gained 1.6%. Tuesday it fell 4.5% on a day the S&P did nothing at all. Whatever was being hedged into Monday’s strength came off again within a session.
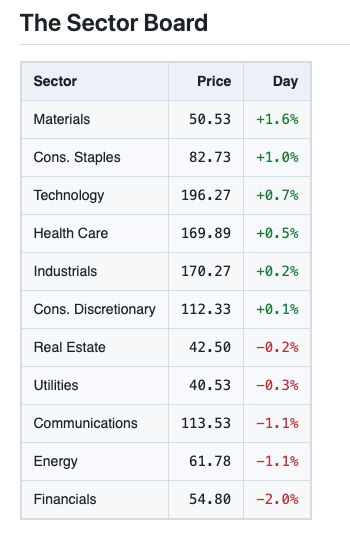
This is the opposite of Monday. Then, Communications and Technology carried a 1.6% index on their own. Tuesday the leadership was Materials and Consumer Staples, and Financials fell two percent. Five of eleven sectors finished red and the index still closed flat, which tells you the weight was spread rather than concentrated.
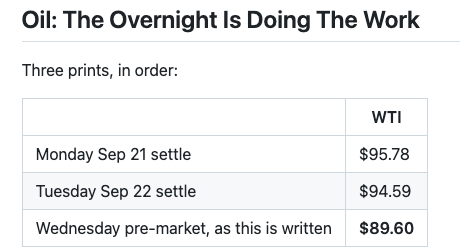
Tuesday was a drift, down 1.2%. The overnight is a gap: roughly five dollars, a little over five percent, in the hours since the close. Brent is near $98.32 on the same move. From Monday’s settle to this morning the US contract has given up $6.18.
Three causes stacked, each larger than the last. Monday it was Qatar working to facilitate a US-Iran agreement. Tuesday the President told the UN he has a “big decision” to make on Iran. Overnight Iran said half the damaged South Pars gas capacity has resumed production. The first two were about whether barrels might return. The third is barrels returning.
Natural gas went the other way entirely, quoted up 6.2% near $3.01.
One thing to be precise about, because it changes what these numbers mean: equities and ETFs stopped trading at Tuesday’s close, so every index, sector and fixed-income figure above is a Tuesday close. Crude, gold, bitcoin and the currency crosses trade nearly around the clock, so those are live quotes from this morning, not Tuesday settles. Mixing the two is how a letter ends up claiming a close that never happened.
Rates Did Nothing, And That Is Worth A Paragraph
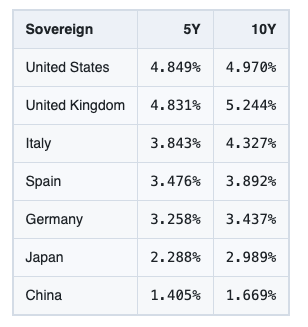
The US 10-year sits at 4.970%, the 5-year at 4.849%. Both are effectively where they were on Monday. Treasuries, high grade and high yield all closed unchanged on the day.
Nick Timiraos posted research worth keeping. It finds that 90% of the rise in the 10-year Treasury yield since August 2020 happened inside the three-day windows around US payroll reports or speeches by the Fed chair, vice chair or Waller — windows that account for just 24% of trading days. Michael Green’s reading of it: that pattern means the move is not investors turning against long-dated debt, it is the market repricing short rates.
Put that next to Monday, when Musalem said further hikes are likely needed. If the 10-year moves on what the Fed says rather than on term premium, then the next repricing arrives on a speech or a payroll print, not gradually.
Trusted Voices
Keith McCullough, Hedgeye — posted last night
“Big differentiated portfolio day for The Fam with Cannabis leading the charge.” Then the part that matters: “We started buying Energy again, so we’ll see how that plays out.”
That is a position, not an opinion, and it is being put on into the worst two-day stretch crude has had in a year. He is buying the thing the tape is selling.
One voice, printed because there was a dated read in front of us. The rest of the panel is left out rather than restated from an older frame.
Before The Open
European futures are firm as this goes out: EuroStoxx 50 futures +0.31%, DAX +0.35%, FTSE +0.36%.
Two things sit under the surface. QQQ closed 0.16% below its 52-week high and SPY 0.77% below its own — the index is at the highs while the average name is not. Netflix is down 23.04% on the year and Tesla 15.75%, both inside the same market that has the Nasdaq 100 up 21.71%.
And the Russians hit port infrastructure in Odesa and a cargo ship in the Black Sea overnight. That has not moved energy, because the South Pars news is larger. It is the kind of thing that stops being ignored the moment the supply story turns.
What We Did About It
We have been taking risk off into this. Eight tickets across Monday and Tuesday — seven short puts bought back across both portfolios and one new one sold. Portfolio 1’s delta came down from 187 after Monday’s closes to 118 after Tuesday’s, and its buying power in use to 6.0%.
Watching, not chasing. When a market closes flat with five sectors red, the index is not telling you what happened underneath it.
Disclaimer
This is not investment advice. Nothing in this letter is a recommendation to buy or sell any security. Grow Your Pile and Squared T Capital publish what we do in our own accounts for education. Options involve substantial risk and are not suitable for every investor. A short put can require you to buy stock at the strike price and can lose more than the premium collected. Past results do not predict future results. Do your own work and consider speaking with a licensed advisor about your circumstances.
Index levels, sector moves, sovereign yields and fixed-income figures in this letter are September 22, 2026 closing figures as they appeared on our own screens. Commodity, currency and bitcoin prices, and the European futures in the final section, are live quotes taken in the pre-market hours of September 23, 2026 and will have moved by the time you read this — they are not September 22 settlement prices. All figures are gross of any subsequent revision. Headlines and quoted comments are reproduced from wire and public feeds; we quote them as published and do not paraphrase them into views their authors did not express. The research finding attributed to Nick Timiraos is his summary of a third-party paper, not our own work. Commentary attributed to Keith McCullough is his own position and is not our recommendation.
Past performance is not indicative of future results, and results shown are those of our own accounts and are not representative of any subscriber’s results. Read the Characteristics and Risks of Standardized Options before trading.
Tony Rihan and Tony Battista Grow Your Pile · Squared T Capital
Every options trade in all three portfolios is published, win or lose, with entry, exit and running P&L at growyourpile.com.