

The Fed Hiked. The Market Went Up Anyway.
The Federal Reserve raised rates on Wednesday, its first hike since 2023, and today the Nasdaq 100 is up 1.8% and the VIX is down 11.7%. If you keep one thing from this letter, keep the shape of that sentence. The reaction is usually more useful than the news, and it doesn’t get much cleaner than a tightening central bank and a bid.
What makes today worth reading is the second part. Wall Street isn’t fading the hike. It’s rebuilding its forecasts around it.
Walter Bloomberg’s account carried the headline: WALL STREET RETHINKS ‘ONE-AND-DONE’ FED HIKE. The post says the Fed’s hawkish September meeting is pushing several banks to add another hike or reduce expected cuts, and it names six of them: Goldman Sachs, Morgan Stanley, NatWest, Rabobank, Swedbank and Commerzbank.
Two caveats on that post before we go further, because they matter. It carries the platform’s “Made with AI” label, and the copy we have is cut off mid-sentence. So we’re using the part that is specific and checkable, which is the list of six banks, and we are leaving the rest of it alone. We’re not finishing a sentence somebody else didn’t finish.
The bigger swing is in Britain. FirstSquawk has JP Morgan now expecting the Bank of England to hike 25 basis points in February 2027. Their previous forecast was two cuts in 2027. That isn’t a tweak to a path, it’s the other direction.
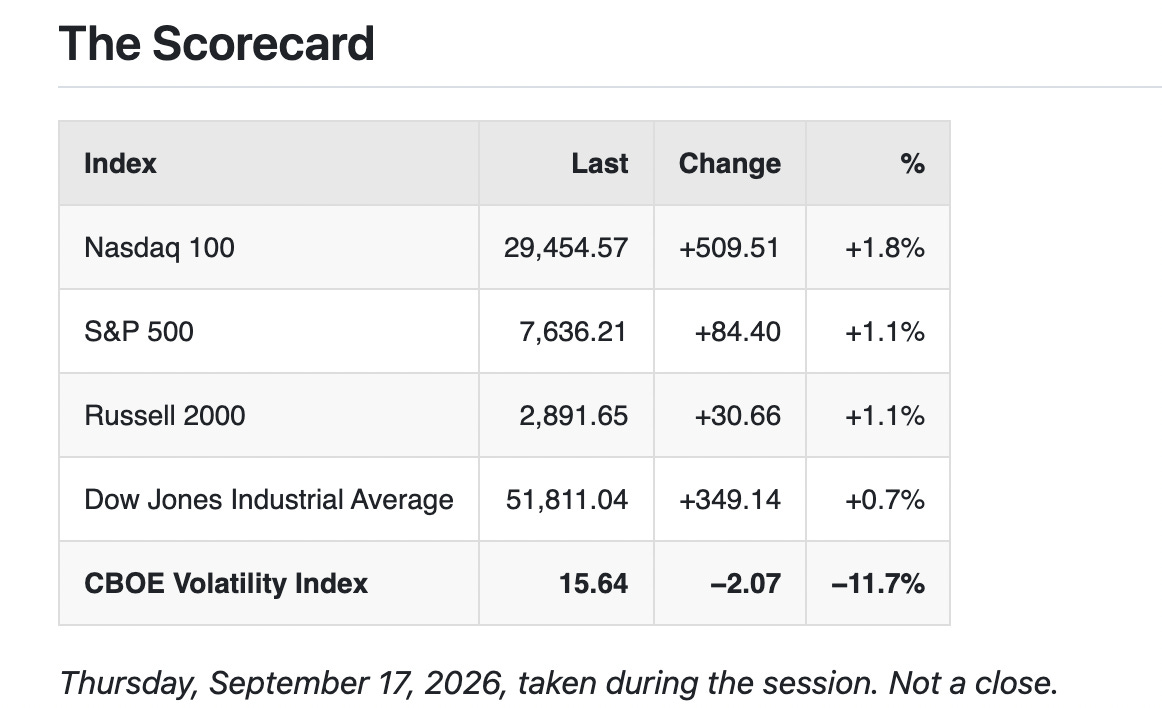
Four equity indices green, and the spread between them tells you what kind of rally this is. The Nasdaq 100 is up 1.8% and the Dow 0.7%, so there’s a point and a tenth of daylight between the tech-heavy index and the thirty industrials. That points straight at the chip names, and we’ll get there.
The S&P and the Russell are both +1.1%. This isn’t a large-cap-only move; the small end came along.
Then the VIX, which is the number of the day. Down 2.07 to 15.64, an 11.7% crush. The change column puts the prior close at 17.71. We published 17.43 on Tuesday, and that was a mid-session read rather than a close, so those two aren’t the same kind of number and we won’t pretend otherwise. What isn’t in doubt is the direction. The day after a rate hike, the fear gauge got taken apart. Hold that thought. There’s a Trusted Voice further down who makes it a lot more interesting.
Thursday, September 17, 2026, taken during the session. Not a close.
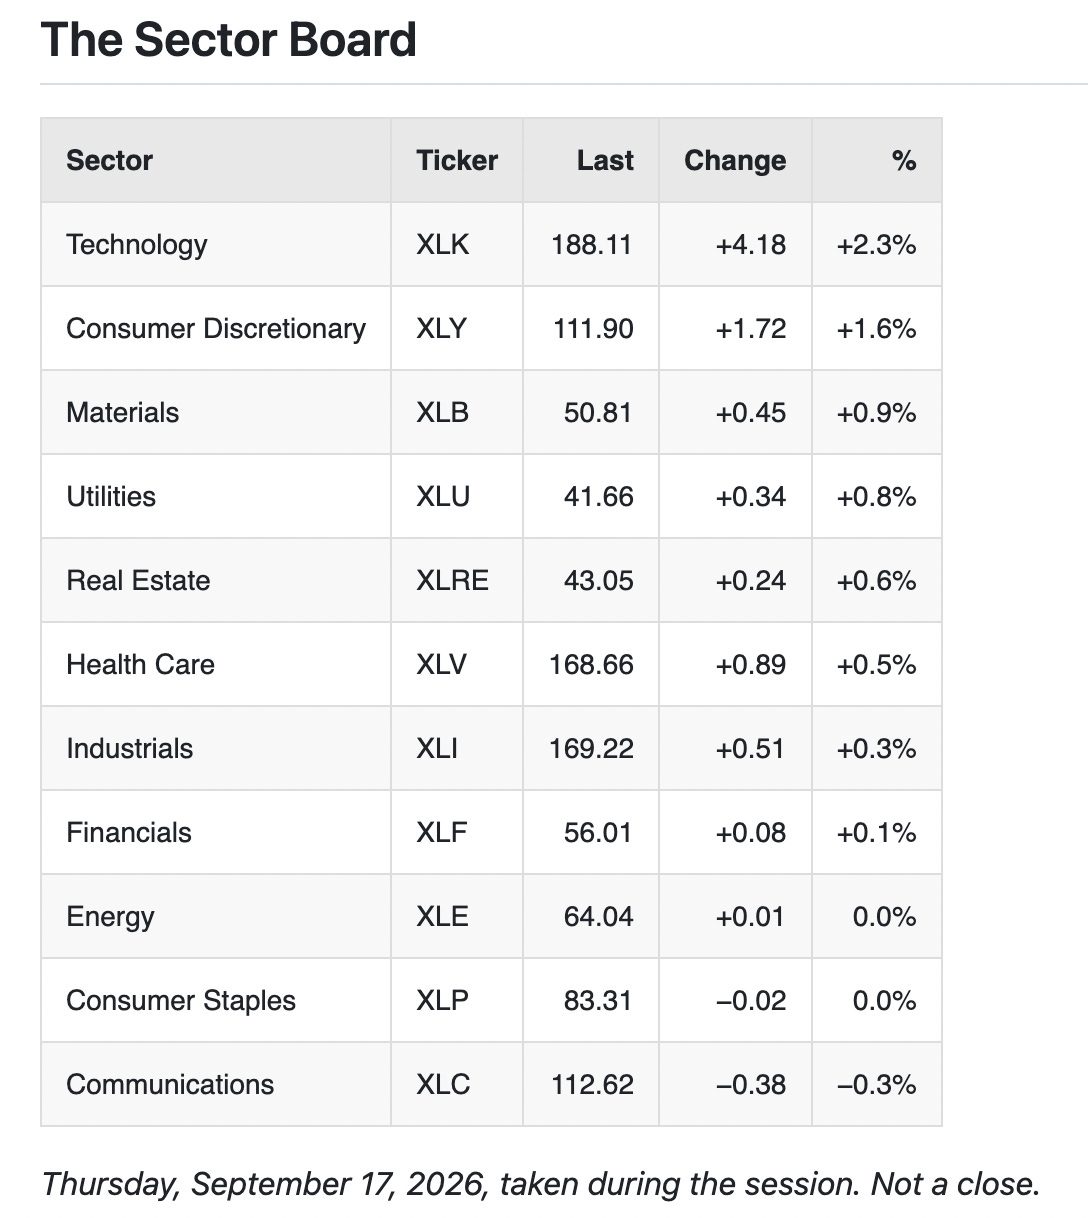
Technology leads at +2.3% and the whole board fits inside 2.6 points.
One sector prints red: Communications at −0.3%. Two round to zero and they round from opposite sides. Energy is a penny higher, Staples two cents lower. We’d call those flat rather than rank one above the other.
Energy is where to look. Crude is down 1.5% today and the energy sector didn’t move. Oil is the strangest thing on this page and it gets its own section.
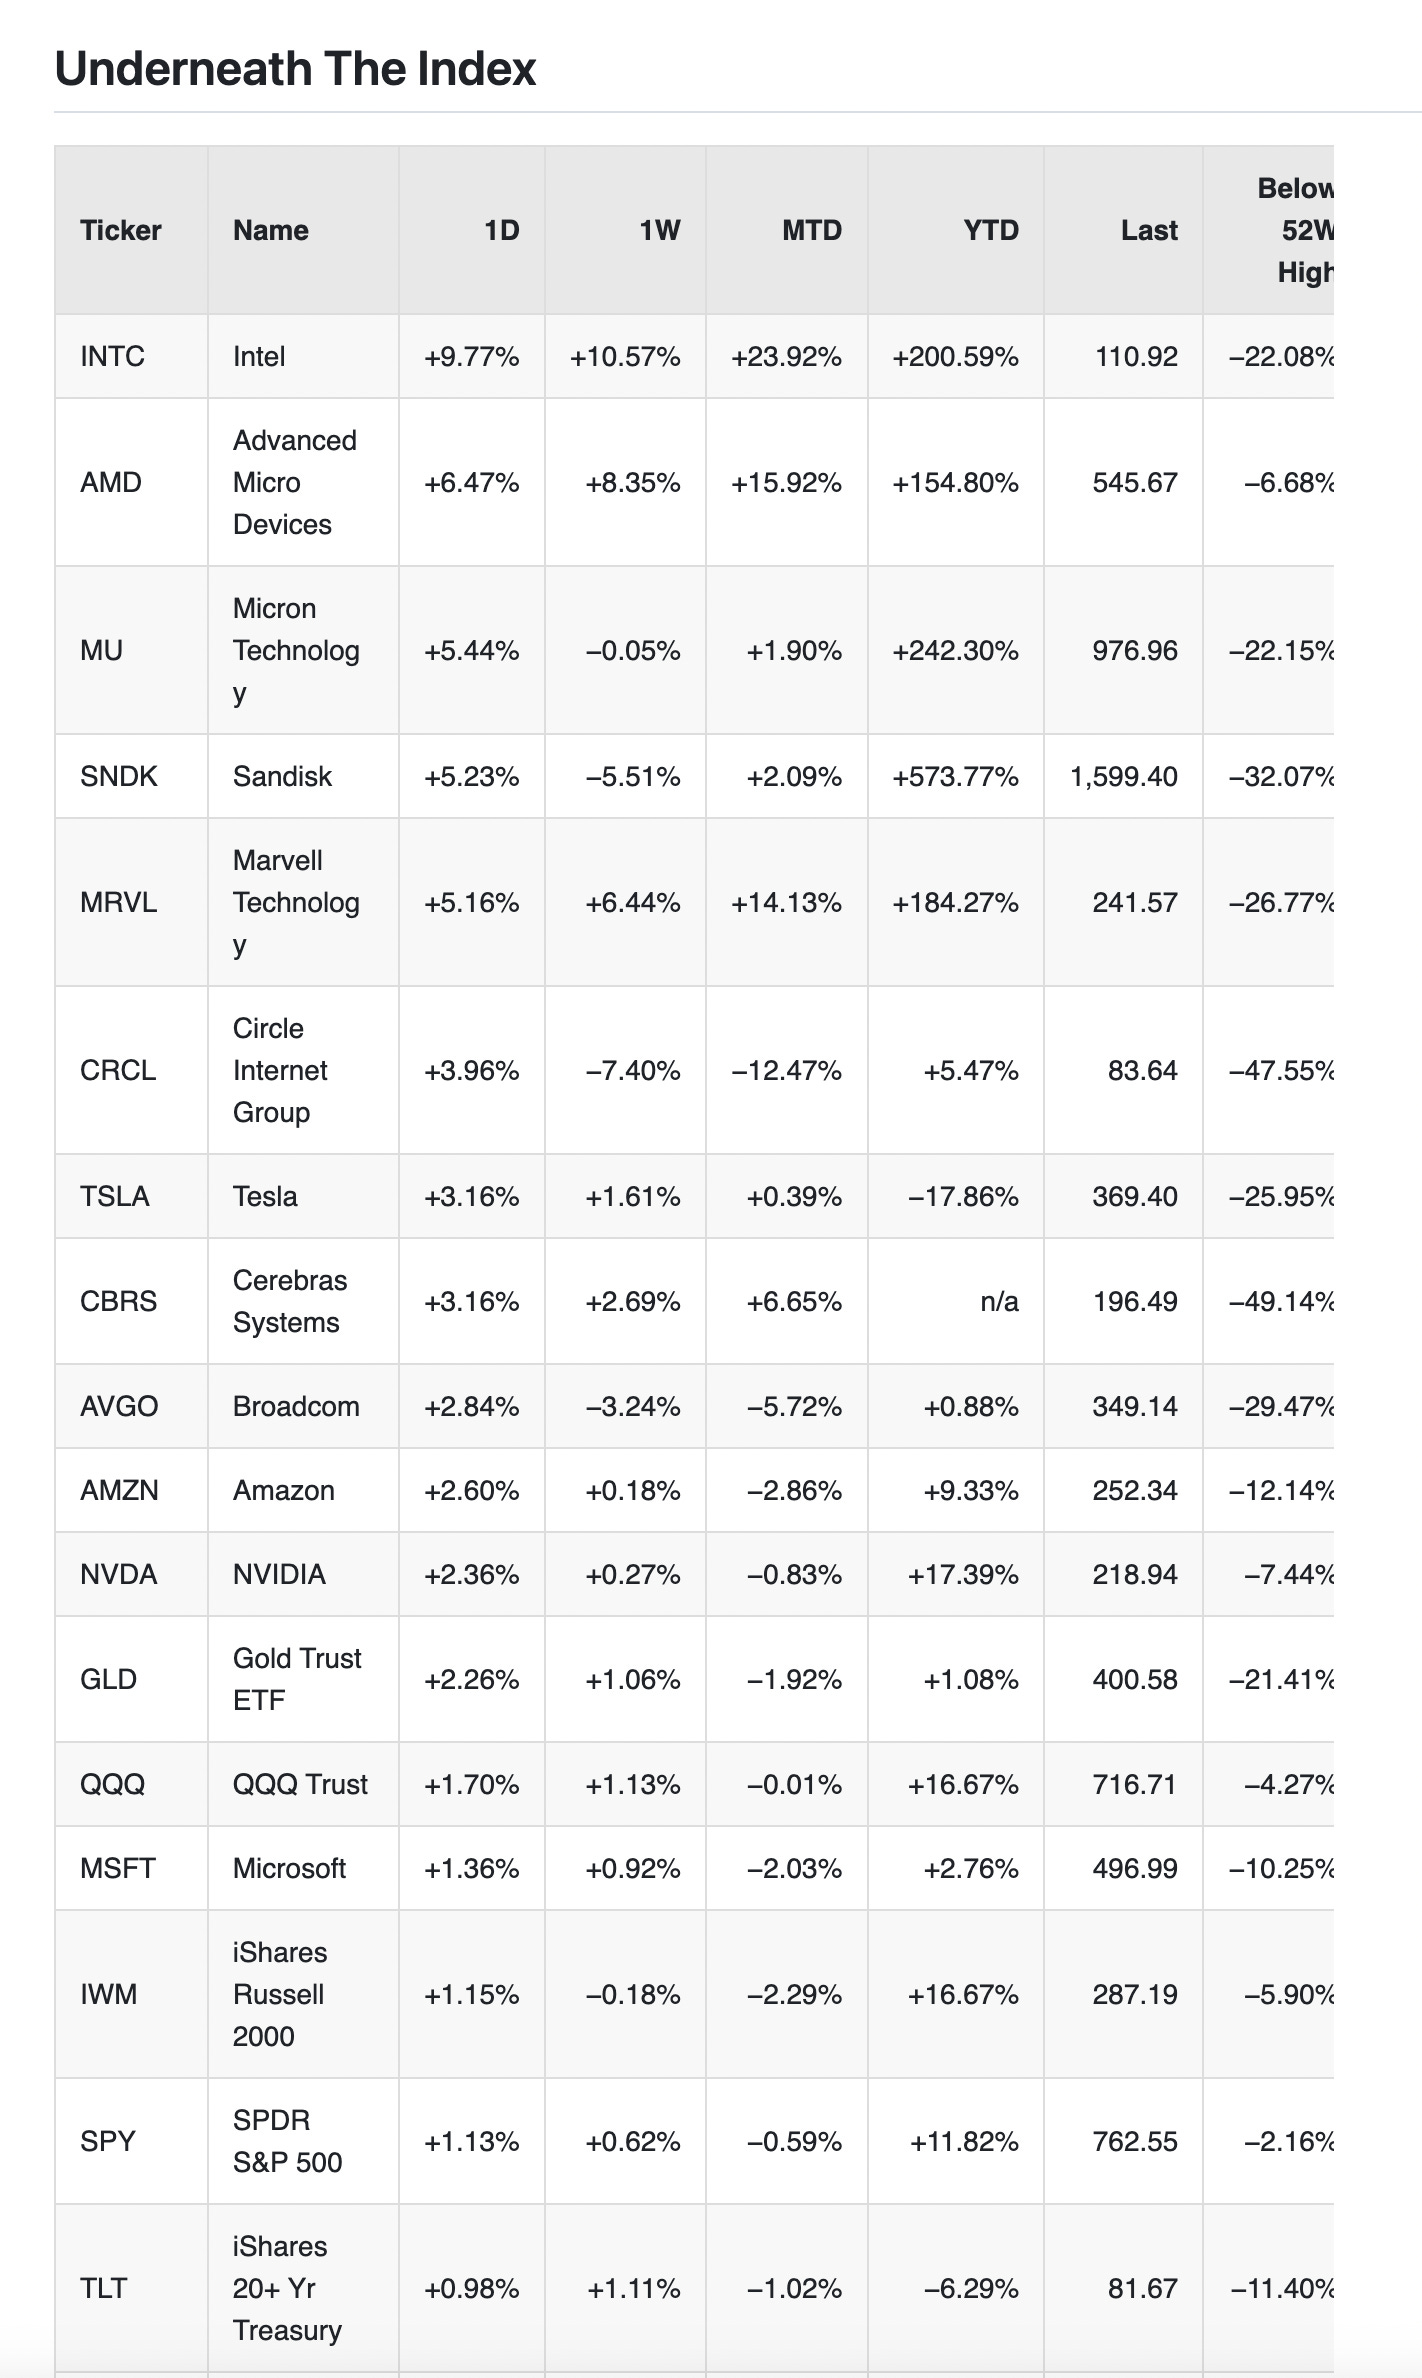
Twenty-one of the twenty-two are green. Before anybody reads that as breadth: this is the list we happen to follow, twenty-two names we picked, and it is not a measurement of the market. We have no advance-decline data today and we’re not going to dress our watchlist up as some.
The chips are the tape. Intel +9.77%, AMD +6.47%, Micron +5.44%, Marvell +5.16%, Broadcom +2.84%, NVIDIA +2.36%. All six of them. Sandisk, the storage name on our board, is +5.23% right alongside.
Intel is up 9.77% today and 10.57% over the past week. Almost the whole week happened in this one session. Its 52-week range runs from 24.45 to 142.35 and it’s 110.92 now, up 200.59% on the year.
The week tells a different story from the day, and that’s worth a second. Four of the six chip names are higher over five sessions: Intel +10.57%, AMD +8.35%, Marvell +6.44%, NVIDIA +0.27%. Micron is a hair lower at −0.05% and Broadcom is down 3.24%. So today isn’t six names continuing. It’s two of them bouncing and four of them extending.
Then look at what those same names have done on the year. Sandisk +573.77%. Micron +242.30%. Intel +200.59%. Marvell +184.27%. AMD +154.80%. And then NVIDIA, the name everybody has an opinion about, at +17.39%, with Broadcom at +0.88%. Same industry, same year, and two of those numbers are from a different planet than the other five.
The big names came along but they didn’t lead. Tesla +3.16%, Amazon +2.60%, Microsoft +1.36%, Meta +0.83%, Apple +0.77%, Alphabet +0.71%. Netflix is the only red name on the board at −0.86%, and of the twenty-one rows that carry a year-to-date figure it’s the worst of them at −19.20%, with Tesla close behind at −17.86%.
Apple is the single stock sitting closest to its own 52-week high, 2.79% below it, and it’s +23.21% on the year. SPY is closer still at 2.16% below. On the day after a rate hike, the index is essentially at the highs.
The broken ones bounced, but they’re still broken. Cerebras +3.16% today and 49.14% below its 52-week high. Circle +3.96% today, 47.55% below its high and −12.47% month to date. A good day off a low base is still a low base. The drawdown column is the one telling the truth about those two.
Bonds and bitcoin. TLT is +0.98% on the day a central bank tightened, and the broad Treasury fund GOVT is +0.4%. Longer paper up more than the blend. We’ll take that at face value and not build a theory on one session. IBIT is +0.92% against bitcoin itself at +0.6%. Call that agreement. Those two prints came off different panels a few minutes apart, not one simultaneous capture, and a few minutes is plenty to open three tenths of a point on a tape that keeps moving.
And gold. Spot is +2.4% and the ETF is +2.26%, so they agree. The column that invites a bad conclusion is the drawdown: GLD is 21.41% below its 52-week high of 509.70. We don’t have a 52-week range for spot gold on this board, so we can’t put the two drawdowns side by side, and we’re not going to let that column imply the metal is 21% off anything. All it says is that the fund printed a higher price at some point in the last twelve months.
What Printed Today, And Why Jobs Is The Story
The economic prints came across Liz Ann Sonders’ feed: actual, estimate, prior, posted straight. She put out data today, not a view, and that’s how we’re using it.
Start with the part that’s unambiguous. Initial jobless claims came in at 196,000 against a 207,000 estimate and a 206,000 prior. Continuing claims were 1.730 million against 1.779 million expected and 1.769 million prior. Both beat, and they beat clean. Fewer people filing, fewer people still collecting. The biggest state increases were Kentucky +1,000, Hawaii +200, Arkansas and Massachusetts +100 apiece. The biggest decreases were California −4,600, Texas −3,000 and Michigan −2,200.
Now the other half of it, which goes the other way.
The Philadelphia Fed’s September employment component printed +11.8 against +27.9 the month before. That’s more than halved. And the New York Fed’s September services index had both the employment and capital spending components contracting, with employment down seven points.
Those things are all in front of us on the same day and they don’t agree. The hard claims data says the labour market is fine. Two separate survey employment components say hiring intentions are rolling over. We are not going to resolve that for you, because we can’t, and anyone telling you today which one wins is guessing in a confident voice.
What we will say is that they measure different things. Claims count people who already lost a job. Survey components ask firms what they intend to do next. Those two can drift apart for months and mean nothing. They can also drift apart right at a turn. Both of those are true, neither is a forecast, and the next print is what settles it.
The rest of the Philadelphia Fed report: headline +37.8 against +32.1 expected, but down from 47.4 the month before. New orders +29.2 versus +30.1 prior. Shipments +27.7, unchanged from prior. And prices paid at +48.9 against +40.9 the month before, eight points higher and accelerating, into a Fed that just raised rates. You don’t need a model to read that one.
Housing is the soft spot and it isn’t close. Starts fell 2.6% month over month against an expected +6.7%, after −9.0% the month before. Permits −2.7% against −1.5% expected, after +4.3%. Pending home sales were the bright spot at +0.3% against −0.1% expected, though the prior month was revised down to −2.6% from −2.3% in the same release, and a month-over-month number is measured off that prior. We’re flagging the revision rather than filing the print under good news.
A 2.6% drop where the estimate was a 6.7% gain is a 9.3-point swing against expectations. Nobody was talking about housing today.
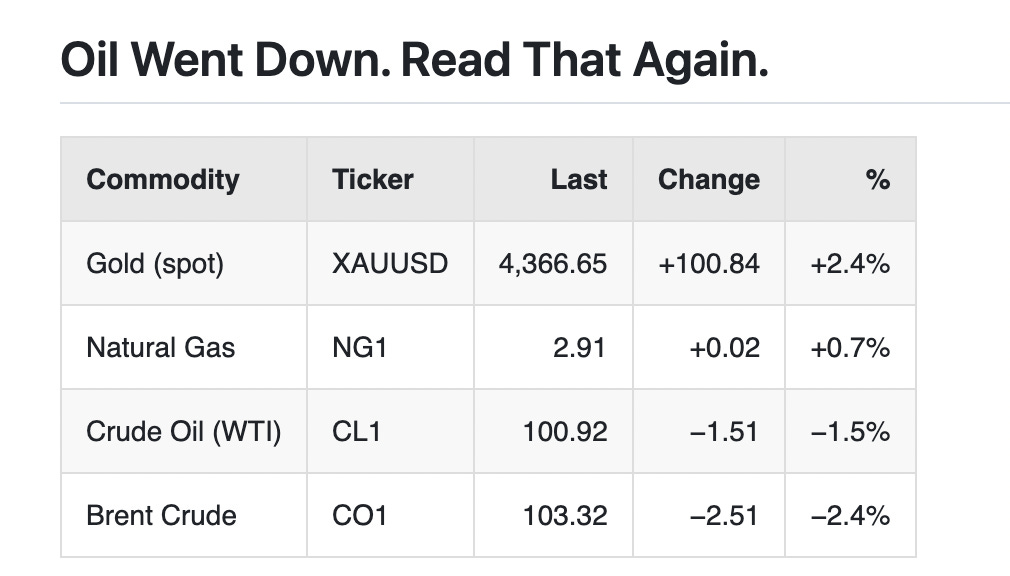
Crude is off 1.5% at 100.92 and Brent is off 2.4% at 103.32. The Brent-WTI spread is $2.40 today. On Tuesday, in this letter, we wrote that it was exactly four dollars.
Here’s what came across the wire today. Three oil pump stations on Saudi Arabia’s East-West pipeline were hit in an attack. The report came in today; the attack itself was last week. An explosion occurred in the Strait of Hormuz. And CENTCOM says that as of September 17 it has redirected 104 commercial vessels.
Pump stations hit, an explosion in the Strait of Hormuz, a hundred and four ships rerouted, and the price of oil fell. We don’t have an explanation for that. We’re not going to manufacture one out of adjectives, and we’d be careful with anyone who does it quickly. It’s on the page. Sit with it.
Natural gas is +0.7% at 2.91, and the EIA reported that US stockpiles rose 44 Bcf last week. Two facts, not a chain.
The metals went the other way from oil. Spot gold is +2.4% at 4,366.65. FirstSquawk had spot silver up 5% at $66.13 an ounce. That’s the wire’s number rather than our board’s, and we’re keeping it in the wire’s words. Hard assets catching a bid the day after a central bank tightens is not the reflex most people would expect.
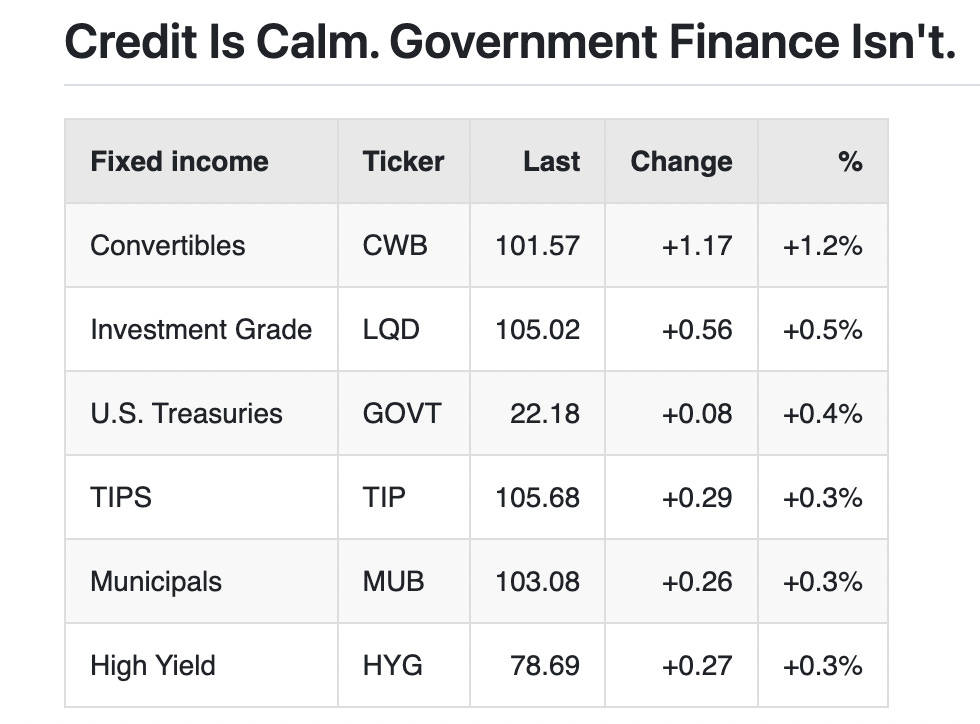
All six green on the day after a hike. Convertibles lead at +1.2%, which makes sense given what equities did, because there’s stock inside a convertible. Investment grade +0.5%, Treasuries +0.4%, and TIPS, municipals and high yield +0.3% each.
Nothing in that table says stress. High yield and investment grade moving together, and moving with government paper, is credit telling you this is about the price of money and not about anybody’s ability to repay.
The bill shows up somewhere else. France’s Prime Minister Lecornu said the 2027 budget deficit, without corrective measures, is seen exceeding 6.5% of GDP, and that the rise in interest rates is seen costing an additional 10 billion euros to finance debt servicing. Both via Le Figaro on the wire today. That second figure is a hiking cycle in one line: rates go up, and the carrying cost of the debt you already owe goes up with them.
Closer to home, Treasury is selling $69 billion of two-year notes, in line with the $69 billion estimate.
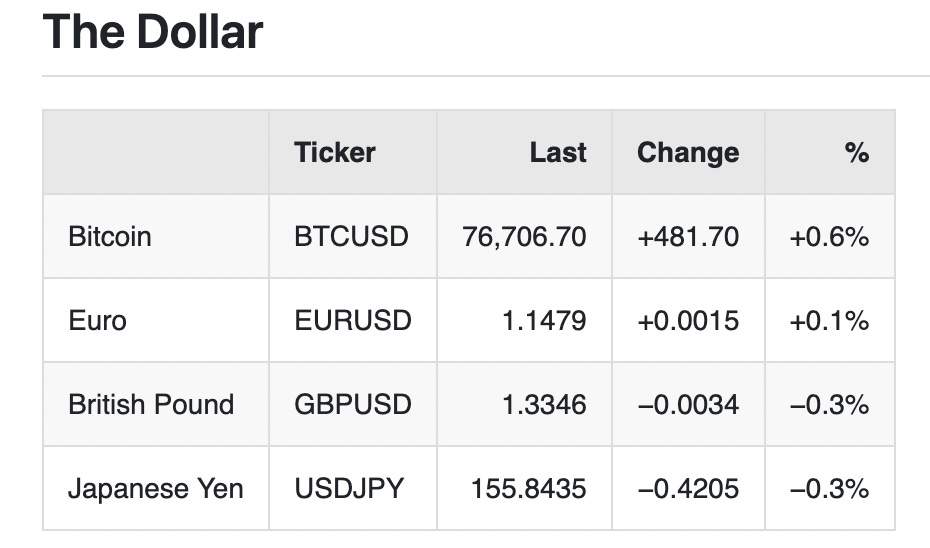
Three currencies, and the dollar went a different way against two of them than it did against the third. It gave up a tenth to the euro and three tenths to the yen, and it picked up three tenths on the pound. Nobody should build a dollar view out of that.
Sterling is the one the dollar gained on, and it happened on the day JP Morgan flipped its Bank of England call from two cuts to a hike. That’s the kind of coincidence that writes itself into a tidy story. We’re leaving it as a coincidence. Three tenths of a percent in one session proves nothing.
Bitcoin is +0.6% at 76,706.70, up with everything else and not leading anything.
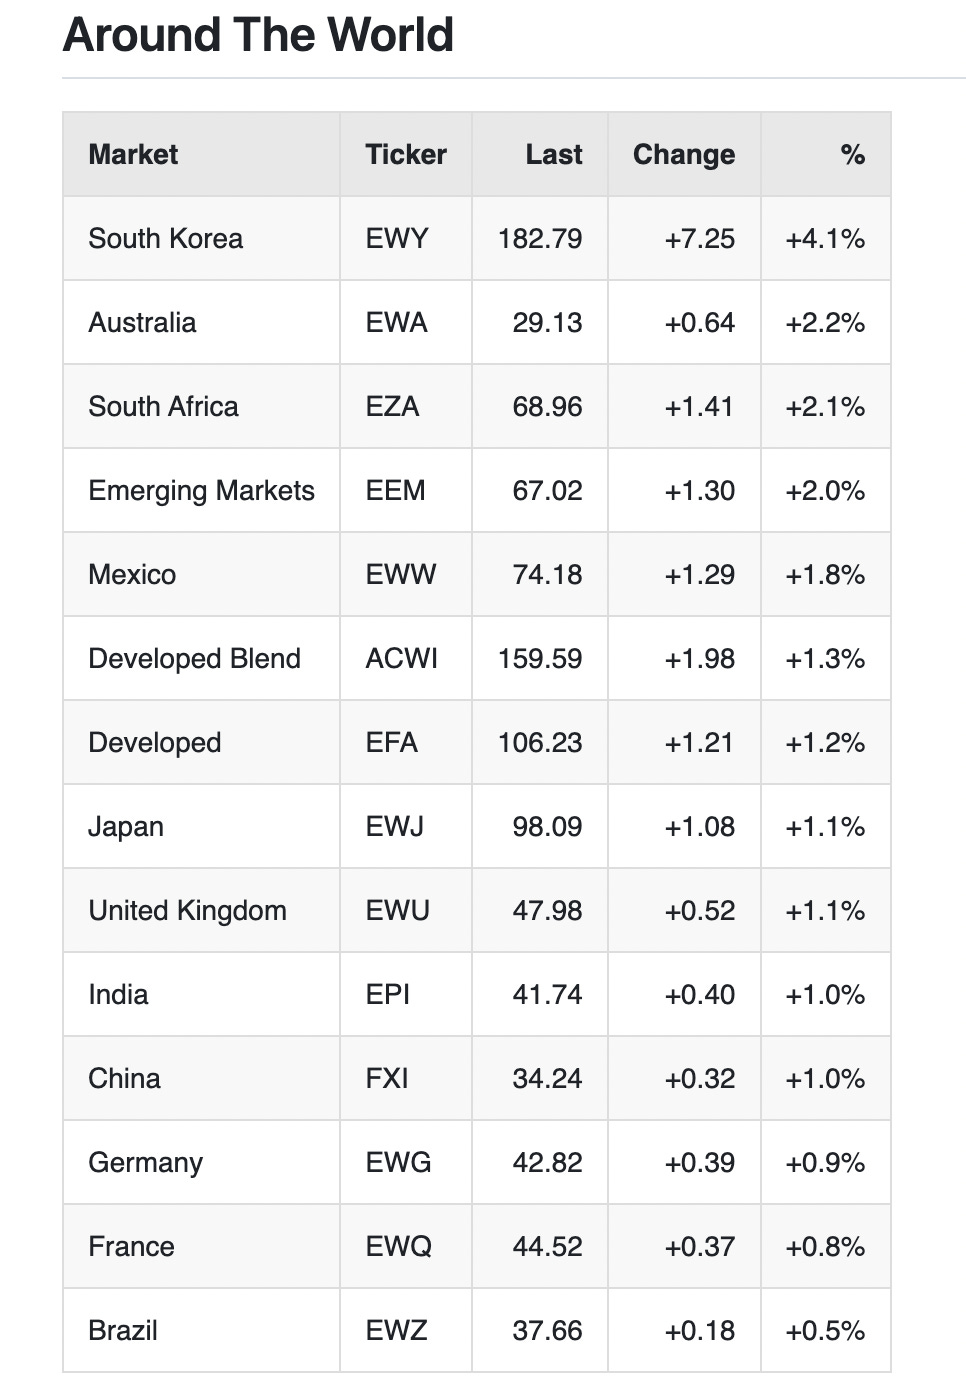
Fourteen markets on our board and all fourteen are green. South Korea is the best of them by a wide margin at +4.1%, close to double the next best, Australia at +2.2%. Brazil is the laggard and it’s still up half a percent.
Korea being the standout on a day every chip name on our board is up fits together nicely, and fitting together nicely is not evidence. You can tell that story after one session or you can wait for the tenth one. We’d wait.
Europe was up on both measures. The wire had the FTSE 100 +1.2%, IBEX +1.13%, DAX +0.77% and CAC 40 +0.58%. Our board carries the dollar-denominated country funds instead: EWU +1.1%, EWG +0.9%, EWQ +0.8%. Those are different instruments, a local-currency index against a fund priced in dollars, so don’t read the gaps between them as disagreement. They’re two ways of saying Europe rallied.
One for the diary. The wire has China and the United States preparing for a Xi-Trump summit scheduled for September 24, with Wang Yi and Rubio having held talks. FXI is +1.0% today.
Trusted Voices
Two today, and one of them lands right on the VIX.
Keith McCullough (@KeithMcCullough), Hedgeye, posted today about an hour before Tony sent this over:
“CHART OF THE DAY: Panic Put Buying Into Yesterday’s Close”
The VIX is down 11.7% today. We’ll let those two sit next to each other and not gild it.
He followed it in the same hour with this:
“ha. If I wanted to waste my precious time today, I’d audit wherever their narrative on stocks had to pivot today vs. when they were panic-buying-puts yesterday”
That’s a jab and he means it as one. His framing, his position, not ours.
Danielle DiMartino Booth (@DiMartinoBooth), CEO and Chief Strategist at QI Research and a former Federal Reserve insider, posted yesterday, the day the Fed hiked:
“small business bankruptcies are up 64% YoY through August, more than 200 companies have closed every month for five months running, and…”
That is where the copy we have ends. Mid-sentence, mid-thought. We’re publishing it truncated rather than completing it, because finishing somebody’s sentence is how a quote turns into a fabrication, and three quarters of a real one beats a whole invented one.
We’re also going to leave it standing on its own rather than wire it into the rest of the letter. Small-business bankruptcies up 64% year over year, on the day a central bank raised rates, is worth noticing. It isn’t a trade and we’re not going to dress it up as one.
Both of them posted other things today. Nearly all of it was notices about television hits, plus a plug for one of Hedgeye’s own products. None of that is a view on this market, so none of it made the letter. We’d rather run two voices than pad it out to five.
What We Actually Did
Portfolio 2 closed five short puts today across four positions: two QQQ September 18 691s, an SPY September 18 748, and IWM September 18 282 and 280. All of them had one day left to run. All five were winners. The five closes came to $842.00.
Battista’s reason, in his own words: “Reducing short-term risk on the big bounce today.”
That’s the entire idea, and it’s deliberately boring. The last day of a winning short put pays you almost nothing and still carries the full risk of the thing. When the index gaps higher and the VIX loses 11.7%, those positions have already done their job. Taking them off into strength is the repeatable version of this business, not the clever version.
It wasn’t a clean-out, though. Portfolio 2 still has nine SPX September 18 butterfly rows open, and September 18 is tomorrow, the September monthly expiration. Every trade in all three portfolios is published on the members site with entry, exit and running P&L.
Bottom Line
Written mid-session, and this is the third time we’ve said it: none of these numbers is a close.
The Fed hiked on Wednesday for the first time since 2023, and the market went up on Thursday. Six banks are adding a hike or trimming expected cuts, and JP Morgan swung from two Bank of England cuts in 2027 to a February hike. That is not a market fading a hawkish Fed. That’s a market rebuilding around one.
The rally is the chips. All six of ours are green, Intel did a week’s work in one session, the Nasdaq 100 beat the Dow by a point and a tenth, and South Korea was the best of the fourteen markets on our board. Those are four descriptions of the same event.
The VIX is down 11.7% the day after a Trusted Voice pointed at panic put buying into the close. Make of that what you want. We’re not going to tell you it’s a top or a bottom, and we’d be suspicious of anybody who does.
The thing to actually carry out of here is the jobs split. Claims beat on both measures. Two separate survey employment components came in soft on the same day. They don’t agree, we’re not forcing them to agree, and the next print is what tells you which one was early.
Oil fell on a day the wire carried three hit pump stations and an explosion in the Strait of Hormuz. We have no explanation. When a market does the opposite of its own headline, that’s usually the most useful thing on the page, even if it takes weeks to find out why.
And housing missed badly while nobody was looking. Starts at −2.6% against +6.7% expected isn’t a rounding error.
Nobody sent us a calendar for the back half of the week, so there’s no calendar in this letter. We’ll take the next print when it comes.
Disclaimer
This is not investment advice. Nothing in this letter is a recommendation to buy or sell any security. Grow Your Pile and Squared T Capital publish what we do in our own accounts for education. Options involve substantial risk and are not suitable for every investor. A short put can require you to buy stock at the strike price and can lose more than the premium collected. Past results do not predict future results. Do your own work and consider speaking with a licensed advisor about your circumstances.
Past performance is not indicative of future results, and results shown are those of our own accounts and are not representative of any subscriber’s results. Read the Characteristics and Risks of Standardized Options before trading.
Tony Rihan and Tony Battista Grow Your Pile
Every options trade in all three portfolios is published, win or lose, with entry, exit and running P&L at growyourpile.com.